Blocked input tax credit for resort construction remains unavailable; interest follows actual utilisation, while delayed payment attracts statutory pe...
Duplicate PAN allocation requires record verification and deactivation reasons before assessment-related transactions can be attributed to an assessee...
Faceless assessment safeguards require requested personal hearings and adequate final show-cause response time, failing which reassessment is required...
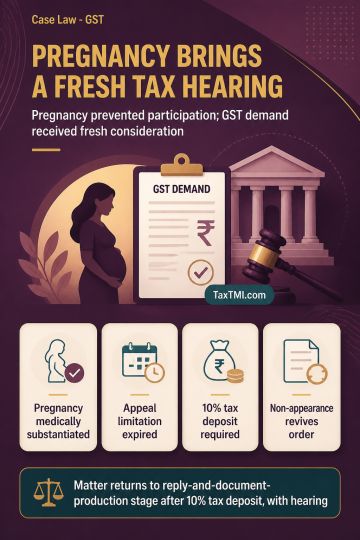
Natural justice in ex parte GST adjudication required fresh consideration where medical records substantiated the proprietor's pregnancy and consequent inability to participate. Expiry of the statutory appellate limitation left no appellate remedy. The ex parte GST demand was set aside subject to deposit of 10% of the tax demanded and remitted from the reply-and-document-production stage, with a reasonable opportunity of hearing. Non-appearance as directed would automatically revive the earlier order.
Natural justice in ex parte GST adjudication required fresh consideration where medical records substantiated the proprietor's pregnancy and consequent inability to participate. Expiry of the statutory appellate limitation left no appellate remedy. The ex parte GST demand was set aside subject to deposit of 10% of the tax demanded and remitted from the reply-and-document-production stage, with a reasonable opportunity of hearing. Non-appearance as directed would automatically revive the earlier order.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918