Income Declaration Scheme declarations can evidence share-capital sources, while round-tripped funds and cash-linked credits require further verificat...
Permanent establishment tests: independent subsidiary premises and principal-to-principal dealings did not create Indian taxability for offshore suppl...
Valuation Officer estimates govern property-value additions once statutory valuation is invoked, requiring fresh consideration of objections and compa...
Waiver of written show-cause notice may prevent a later procedural challenge after participation in customs adjudication, preserving statutory appella...
Retrospective invalidity of ocean-freight IGST supports refunds despite non-party status and prior credit utilisation, subject to authorised appeal gr...
Page of 4902
Press 'Enter' after typing page number.
221 to 240 of 98028 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
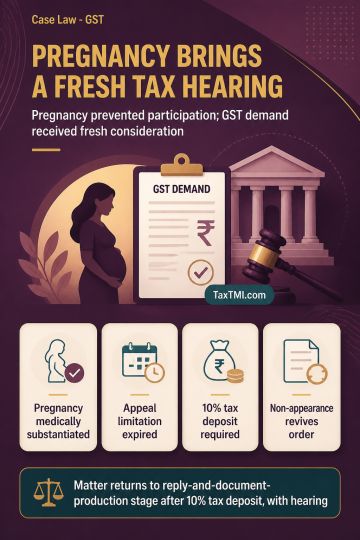
Natural justice in ex parte GST adjudication required fresh consideration where medical records substantiated the proprietor's pregnancy and consequent inability to participate. Expiry of the statutory appellate limitation left no appellate remedy. The ex parte GST demand was set aside subject to deposit of 10% of the tax demanded and remitted from the reply-and-document-production stage, with a reasonable opportunity of hearing. Non-appearance as directed would automatically revive the earlier order.
Natural justice in ex parte GST adjudication required fresh consideration where medical records substantiated the proprietor's pregnancy and consequent inability to participate. Expiry of the statutory appellate limitation left no appellate remedy. The ex parte GST demand was set aside subject to deposit of 10% of the tax demanded and remitted from the reply-and-document-production stage, with a reasonable opportunity of hearing. Non-appearance as directed would automatically revive the earlier order.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4902