Cross-segment derivatives manipulation: integrated order patterns can support interim restraints, while director liability requires responsibility, co...
Power bank definition limits the customs-duty exclusion, preserving concessional treatment for stationary, grid-scale and industrial battery storage s...
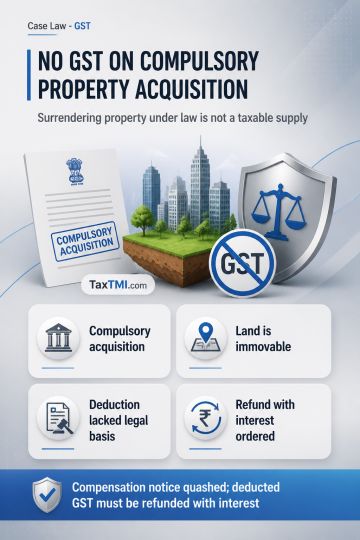
Compulsory acquisition of land and buildings under the State's eminent-domain power is an expropriation, not a supply of goods or services for GST purposes. Land and buildings attached to land are immovable property, and landowners do not sell goods or provide services merely by surrendering property pursuant to statutory acquisition. GST deducted from compensation for such acquisition therefore lacks statutory basis. The deduction was treated as exceeding legal authority, with the affected compensation notice quashed to that extent and refund of the deducted GST with interest directed.
Compulsory acquisition of land and buildings under the State's eminent-domain power is an expropriation, not a supply of goods or services for GST purposes. Land and buildings attached to land are immovable property, and landowners do not sell goods or provide services merely by surrendering property pursuant to statutory acquisition. GST deducted from compensation for such acquisition therefore lacks statutory basis. The deduction was treated as exceeding legal authority, with the affected compensation notice quashed to that extent and refund of the deducted GST with interest directed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4905