Timely pronouncement of reserved judgments requires defined timelines, transparency measures, and remedial pathways to protect liberty and effective j...
Settlement-price depression requires proof of manipulation, not merely short exposure, late selling, or below-market orders, preserving disclosure pen...
Income Declaration Scheme declarations can evidence share-capital sources, while round-tripped funds and cash-linked credits require further verificat...
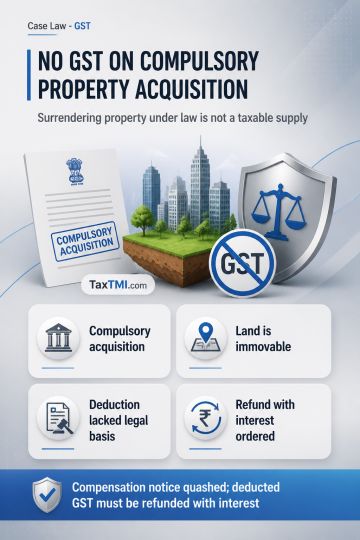
Compulsory acquisition of land and buildings under the State's eminent-domain power is an expropriation, not a supply of goods or services for GST purposes. Land and buildings attached to land are immovable property, and landowners do not sell goods or provide services merely by surrendering property pursuant to statutory acquisition. GST deducted from compensation for such acquisition therefore lacks statutory basis. The deduction was treated as exceeding legal authority, with the affected compensation notice quashed to that extent and refund of the deducted GST with interest directed.
Compulsory acquisition of land and buildings under the State's eminent-domain power is an expropriation, not a supply of goods or services for GST purposes. Land and buildings attached to land are immovable property, and landowners do not sell goods or provide services merely by surrendering property pursuant to statutory acquisition. GST deducted from compensation for such acquisition therefore lacks statutory basis. The deduction was treated as exceeding legal authority, with the affected compensation notice quashed to that extent and refund of the deducted GST with interest directed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4912