Transfer-pricing aggregation of distinct support-service and subcontract transactions was rejected, while debt-free receivables attracted no notional ...
Customs exemptions cover photovoltaic assembly machinery and PVF backsheets, while fully declared cleared imports may avoid confiscation and penalties...
Specific tariff classification for LCD devices overrides treatment as electricity-meter parts, defeating differential duty, extended limitation, and p...
Stayed disciplinary punishment does not establish unfitness for insolvency professional registration; reconsideration must disregard mere pendency of ...
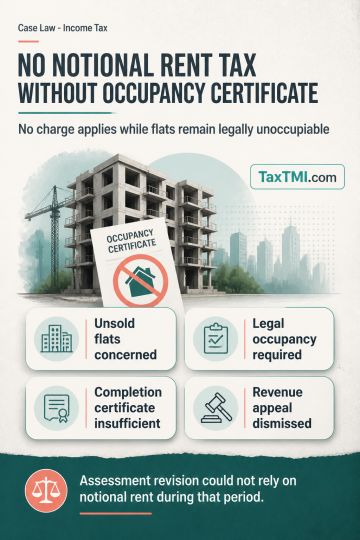
Notional rental income under Section 23(1)(a) is not chargeable on unsold flats during a period in which they are legally unoccupiable because no occupancy certificate has been issued. A completion certificate alone does not establish legal occupiability for this purpose. Consequently, notional rental income cannot form the basis for revision of an assessment for that period, and the Revenue's appeal was dismissed.
Notional rental income under Section 23(1)(a) is not chargeable on unsold flats during a period in which they are legally unoccupiable because no occupancy certificate has been issued. A completion certificate alone does not establish legal occupiability for this purpose. Consequently, notional rental income cannot form the basis for revision of an assessment for that period, and the Revenue's appeal was dismissed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915