Customs transaction value rejection requires communicated reasonable doubt, while written reassessment acceptance preserves challenges to enhanced val...
Challenge-mechanism compliance clarifications permitted, while unilateral revised resolution plans may be refused under creditors' commercial discreti...
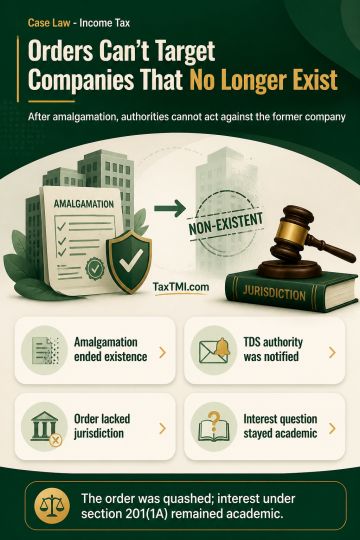
Jurisdiction over an amalgamating company ends when it ceases to exist following amalgamation. A section 201 order issued and served in the former company's name, despite prior notification to the TDS authority, suffers a jurisdictional defect; referring to the successor company in the body of the order does not cure it. The order was void ab initio and quashed, while the issue of interest under section 201(1A) remained academic.
Jurisdiction over an amalgamating company ends when it ceases to exist following amalgamation. A section 201 order issued and served in the former company's name, despite prior notification to the TDS authority, suffers a jurisdictional defect; referring to the successor company in the body of the order does not cure it. The order was void ab initio and quashed, while the issue of interest under section 201(1A) remained academic.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4910