Extended reassessment limitation in search cases requires asset-linked escaped income, invalidating additions based only on unexplained money or expen...
Enhanced tolerance band under section 43CA applies retrospectively, deleting qualifying deemed-sale additions while disputed stamp valuation requires ...
Customs transaction value rejection requires communicated reasonable doubt, while written reassessment acceptance preserves challenges to enhanced val...
Challenge-mechanism compliance clarifications permitted, while unilateral revised resolution plans may be refused under creditors' commercial discreti...
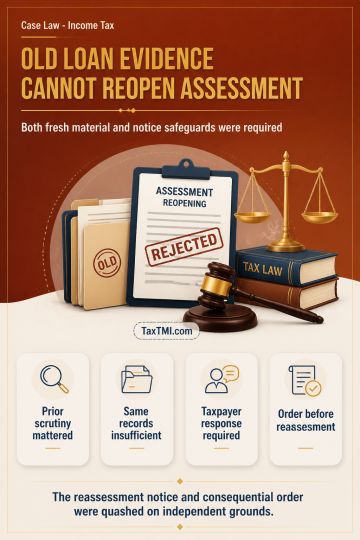
Reassessment of a loan credit previously examined in scrutiny cannot rest on the same confirmation, bank statements and balance sheet without fresh information or tangible material; adopting a different view is an impermissible change of opinion. Separately, an electronic notice served on or after 1 April 2021 must follow section 148A: a show-cause notice, supply of material, consideration of the taxpayer's reply, and an order before issuing a notice under section 148. Failure to follow this sequence invalidates reassessment. On these independent grounds, the reassessment notice and consequential order were quashed, without deciding the loan-credit addition on merits.
Reassessment of a loan credit previously examined in scrutiny cannot rest on the same confirmation, bank statements and balance sheet without fresh information or tangible material; adopting a different view is an impermissible change of opinion. Separately, an electronic notice served on or after 1 April 2021 must follow section 148A: a show-cause notice, supply of material, consideration of the taxpayer's reply, and an order before issuing a notice under section 148. Failure to follow this sequence invalidates reassessment. On these independent grounds, the reassessment notice and consequential order were quashed, without deciding the loan-credit addition on merits.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4912