Blocked input tax credit for resort construction remains unavailable; interest follows actual utilisation, while delayed payment attracts statutory pe...
Duplicate PAN allocation requires record verification and deactivation reasons before assessment-related transactions can be attributed to an assessee...
Page of 4916
Press 'Enter' after typing page number.
681 to 700 of 98302 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
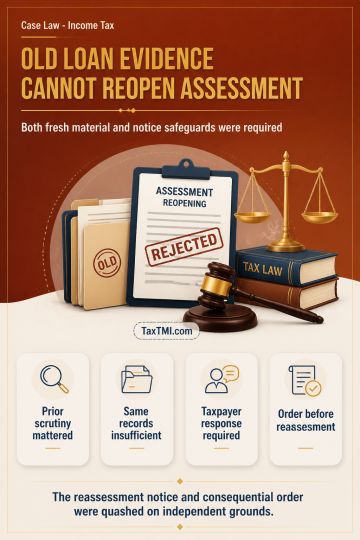
Reassessment of a loan credit previously examined in scrutiny cannot rest on the same confirmation, bank statements and balance sheet without fresh information or tangible material; adopting a different view is an impermissible change of opinion. Separately, an electronic notice served on or after 1 April 2021 must follow section 148A: a show-cause notice, supply of material, consideration of the taxpayer's reply, and an order before issuing a notice under section 148. Failure to follow this sequence invalidates reassessment. On these independent grounds, the reassessment notice and consequential order were quashed, without deciding the loan-credit addition on merits.
Reassessment of a loan credit previously examined in scrutiny cannot rest on the same confirmation, bank statements and balance sheet without fresh information or tangible material; adopting a different view is an impermissible change of opinion. Separately, an electronic notice served on or after 1 April 2021 must follow section 148A: a show-cause notice, supply of material, consideration of the taxpayer's reply, and an order before issuing a notice under section 148. Failure to follow this sequence invalidates reassessment. On these independent grounds, the reassessment notice and consequential order were quashed, without deciding the loan-credit addition on merits.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916