Split consignment classification treated complementary motorcycle parts as one imported motorcycle, sustaining valuation, confiscation and importer li...
Page of 4905
Press 'Enter' after typing page number.
241 to 260 of 98083 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
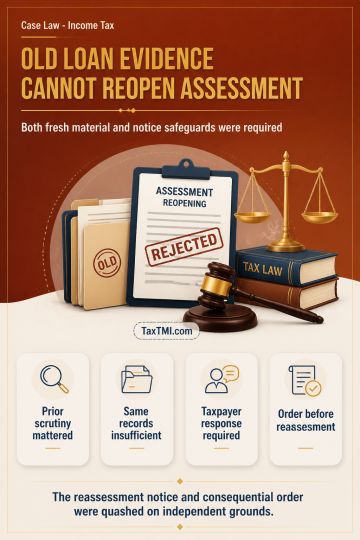
Reassessment of a loan credit previously examined in scrutiny cannot rest on the same confirmation, bank statements and balance sheet without fresh information or tangible material; adopting a different view is an impermissible change of opinion. Separately, an electronic notice served on or after 1 April 2021 must follow section 148A: a show-cause notice, supply of material, consideration of the taxpayer's reply, and an order before issuing a notice under section 148. Failure to follow this sequence invalidates reassessment. On these independent grounds, the reassessment notice and consequential order were quashed, without deciding the loan-credit addition on merits.
Reassessment of a loan credit previously examined in scrutiny cannot rest on the same confirmation, bank statements and balance sheet without fresh information or tangible material; adopting a different view is an impermissible change of opinion. Separately, an electronic notice served on or after 1 April 2021 must follow section 148A: a show-cause notice, supply of material, consideration of the taxpayer's reply, and an order before issuing a notice under section 148. Failure to follow this sequence invalidates reassessment. On these independent grounds, the reassessment notice and consequential order were quashed, without deciding the loan-credit addition on merits.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4905