Transfer-pricing aggregation of distinct support-service and subcontract transactions was rejected, while debt-free receivables attracted no notional ...
Customs exemptions cover photovoltaic assembly machinery and PVF backsheets, while fully declared cleared imports may avoid confiscation and penalties...
Specific tariff classification for LCD devices overrides treatment as electricity-meter parts, defeating differential duty, extended limitation, and p...
Stayed disciplinary punishment does not establish unfitness for insolvency professional registration; reconsideration must disregard mere pendency of ...
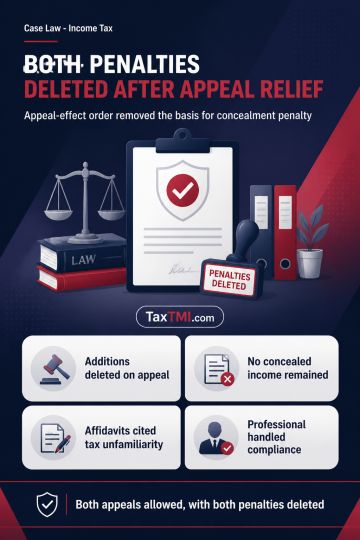
Deletion of reassessment additions through an appeal-effect order removed the basis for concealment penalty, as no concealed income remained when the penalty order was passed. The Tribunal therefore deleted the concealment penalty. Penalty for non-compliance with statutory notices was also deleted where the assessee had stated, through affidavits, unfamiliarity with tax law and reliance on a professional for compliance. The Tribunal treated these circumstances as warranting relief in the interest of justice, allowing both appeals and deleting both penalties.
Deletion of reassessment additions through an appeal-effect order removed the basis for concealment penalty, as no concealed income remained when the penalty order was passed. The Tribunal therefore deleted the concealment penalty. Penalty for non-compliance with statutory notices was also deleted where the assessee had stated, through affidavits, unfamiliarity with tax law and reliance on a professional for compliance. The Tribunal treated these circumstances as warranting relief in the interest of justice, allowing both appeals and deleting both penalties.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915