Infrastructure-development deduction remains available to EPC contractors when substantive statutory conditions outweigh contractor labels in agreemen...
Explained Investment Sources: documented gifts and traceable salary savings supported deletion of additions for property and mutual-fund SIP investmen...
Internal comparable pricing supports arm's-length interest on compulsorily convertible debentures, preventing their recharacterisation as equity for t...
Nominee director protection shields independent financial-institution appointees from criminal liability where they lack involvement in deposit defaul...
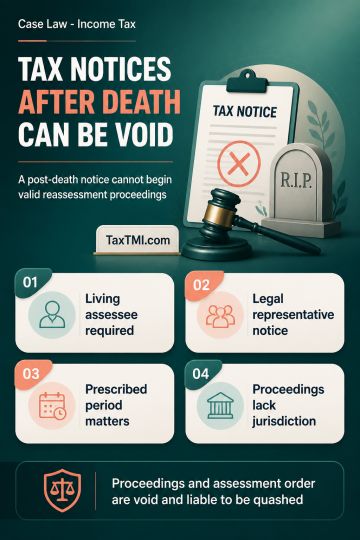
Reassessment proceedings initiated by a notice issued in the name of an assessee already deceased are jurisdictionally defective. A valid reassessment notice must be addressed to a living assessee or, where permitted, to the legal representative. Provisions allowing continuation of existing proceedings against legal representatives do not cure proceedings initiated only after the assessee's death. Where no fresh notice is issued to the legal representatives within the prescribed period, the reassessment lacks jurisdiction. The notice, consequential reassessment proceedings and assessment order are void in law and liable to be quashed.
Reassessment proceedings initiated by a notice issued in the name of an assessee already deceased are jurisdictionally defective. A valid reassessment notice must be addressed to a living assessee or, where permitted, to the legal representative. Provisions allowing continuation of existing proceedings against legal representatives do not cure proceedings initiated only after the assessee's death. Where no fresh notice is issued to the legal representatives within the prescribed period, the reassessment lacks jurisdiction. The notice, consequential reassessment proceedings and assessment order are void in law and liable to be quashed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918