Limitation after transfer-pricing remand: fresh TPO reference did not extend the assessment deadline, rendering the consequential assessment time-barr...
Interim judicial restraint on tax deduction prevents default, while supporting reasonable cause and penalty deletion for foreign-leg LFC reimbursement...
Palmolein classification defeated the crude-oil concession; material misdeclaration sustained recovery and confiscation, while separate false-document...
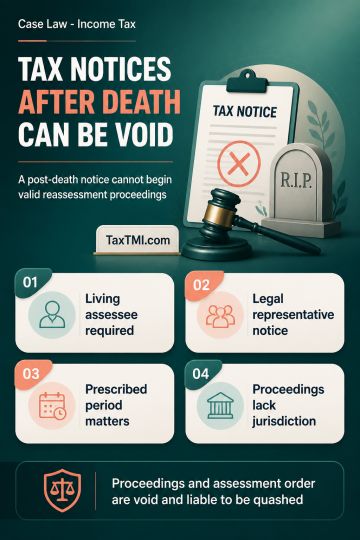
Reassessment proceedings initiated by a notice issued in the name of an assessee already deceased are jurisdictionally defective. A valid reassessment notice must be addressed to a living assessee or, where permitted, to the legal representative. Provisions allowing continuation of existing proceedings against legal representatives do not cure proceedings initiated only after the assessee's death. Where no fresh notice is issued to the legal representatives within the prescribed period, the reassessment lacks jurisdiction. The notice, consequential reassessment proceedings and assessment order are void in law and liable to be quashed.
Reassessment proceedings initiated by a notice issued in the name of an assessee already deceased are jurisdictionally defective. A valid reassessment notice must be addressed to a living assessee or, where permitted, to the legal representative. Provisions allowing continuation of existing proceedings against legal representatives do not cure proceedings initiated only after the assessee's death. Where no fresh notice is issued to the legal representatives within the prescribed period, the reassessment lacks jurisdiction. The notice, consequential reassessment proceedings and assessment order are void in law and liable to be quashed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4900