Suspension of insolvency professional registration prevents continued Resolution Professional appointments and restricts interim stays that effectivel...
Original works exemption for railway contracts depends on actual integrated construction scope, while accessible tax data defeats suppression allegati...
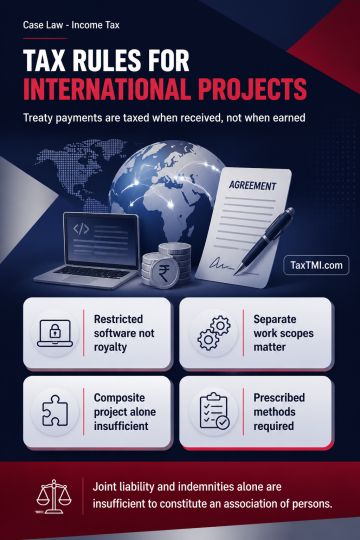
Royalty and fees for technical services under the India-Germany DTAA are taxable on receipt rather than accrual basis. Consideration for restricted, non-exclusive standard software licences that do not transfer copyright rights is not royalty under the Act or treaty. Separate scopes of work, invoicing, consideration and no profit-and-loss sharing prevent consortium members from constituting an association of persons; joint and several liability and indemnities alone are insufficient. Offshore equipment-supply income is not taxable in India merely because it forms part of a composite project. Transfer-pricing adjustments require a prescribed method and cannot rest on an ad hoc mark-up where transaction differences are reconciled and benchmarking is undisputed.
Royalty and fees for technical services under the India-Germany DTAA are taxable on receipt rather than accrual basis. Consideration for restricted, non-exclusive standard software licences that do not transfer copyright rights is not royalty under the Act or treaty. Separate scopes of work, invoicing, consideration and no profit-and-loss sharing prevent consortium members from constituting an association of persons; joint and several liability and indemnities alone are insufficient. Offshore equipment-supply income is not taxable in India merely because it forms part of a composite project. Transfer-pricing adjustments require a prescribed method and cannot rest on an ad hoc mark-up where transaction differences are reconciled and benchmarking is undisputed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4905