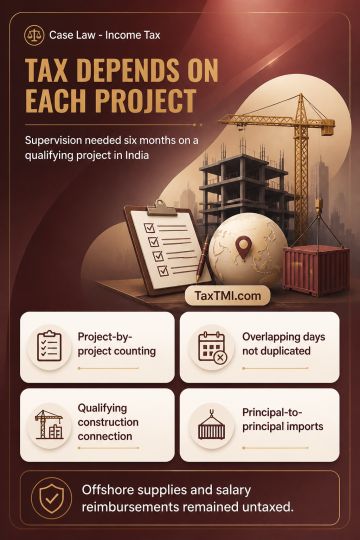
Supervisory permanent establishment requires project-wise duration and qualifying construction nexus; offshore supplies and salary reimbursements rema...
Page of 4916
Press 'Enter' after typing page number.
821 to 840 of 98302 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
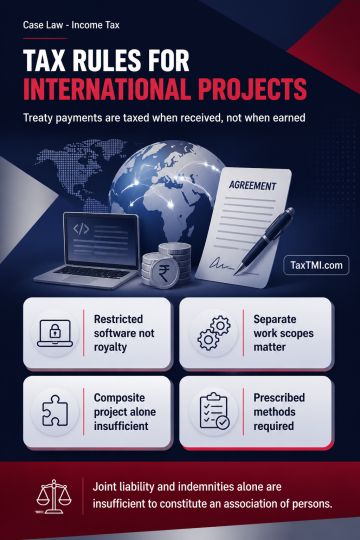
Royalty and fees for technical services under the India-Germany DTAA are taxable on receipt rather than accrual basis. Consideration for restricted, non-exclusive standard software licences that do not transfer copyright rights is not royalty under the Act or treaty. Separate scopes of work, invoicing, consideration and no profit-and-loss sharing prevent consortium members from constituting an association of persons; joint and several liability and indemnities alone are insufficient. Offshore equipment-supply income is not taxable in India merely because it forms part of a composite project. Transfer-pricing adjustments require a prescribed method and cannot rest on an ad hoc mark-up where transaction differences are reconciled and benchmarking is undisputed.
Royalty and fees for technical services under the India-Germany DTAA are taxable on receipt rather than accrual basis. Consideration for restricted, non-exclusive standard software licences that do not transfer copyright rights is not royalty under the Act or treaty. Separate scopes of work, invoicing, consideration and no profit-and-loss sharing prevent consortium members from constituting an association of persons; joint and several liability and indemnities alone are insufficient. Offshore equipment-supply income is not taxable in India merely because it forms part of a composite project. Transfer-pricing adjustments require a prescribed method and cannot rest on an ad hoc mark-up where transaction differences are reconciled and benchmarking is undisputed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916