Income Declaration Scheme declarations can evidence share-capital sources, while round-tripped funds and cash-linked credits require further verificat...
Permanent establishment tests: independent subsidiary premises and principal-to-principal dealings did not create Indian taxability for offshore suppl...
Valuation Officer estimates govern property-value additions once statutory valuation is invoked, requiring fresh consideration of objections and compa...
Waiver of written show-cause notice may prevent a later procedural challenge after participation in customs adjudication, preserving statutory appella...
Retrospective invalidity of ocean-freight IGST supports refunds despite non-party status and prior credit utilisation, subject to authorised appeal gr...
Additional evidence in departmental appeals may include show-cause-notice material without introducing a new case where it merely corroborates existin...
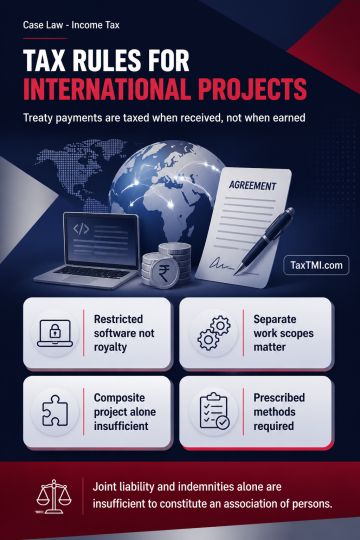
Royalty and fees for technical services under the India-Germany DTAA are taxable on receipt rather than accrual basis. Consideration for restricted, non-exclusive standard software licences that do not transfer copyright rights is not royalty under the Act or treaty. Separate scopes of work, invoicing, consideration and no profit-and-loss sharing prevent consortium members from constituting an association of persons; joint and several liability and indemnities alone are insufficient. Offshore equipment-supply income is not taxable in India merely because it forms part of a composite project. Transfer-pricing adjustments require a prescribed method and cannot rest on an ad hoc mark-up where transaction differences are reconciled and benchmarking is undisputed.
Royalty and fees for technical services under the India-Germany DTAA are taxable on receipt rather than accrual basis. Consideration for restricted, non-exclusive standard software licences that do not transfer copyright rights is not royalty under the Act or treaty. Separate scopes of work, invoicing, consideration and no profit-and-loss sharing prevent consortium members from constituting an association of persons; joint and several liability and indemnities alone are insufficient. Offshore equipment-supply income is not taxable in India merely because it forms part of a composite project. Transfer-pricing adjustments require a prescribed method and cannot rest on an ad hoc mark-up where transaction differences are reconciled and benchmarking is undisputed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4905