Clubbing of income from gifted property failed where the claim surfaced after reassessment limitation, sustaining capital-gains assessment in spouse's...
Employee stock-option discount qualifies as revenue expenditure, while royalty and service comparables require reliable functional and transactional b...
Special insurance income computation preserves statutory deductions while limiting transfer-pricing, withholding and disallowance adjustments for gene...
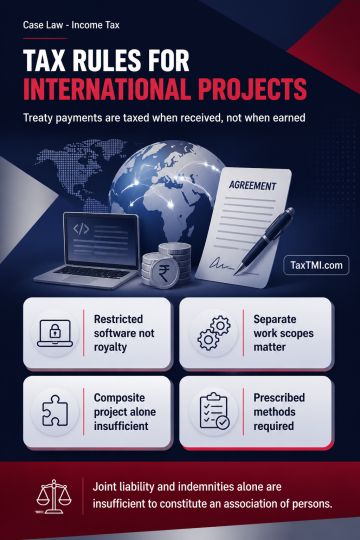
Royalty and fees for technical services under the India-Germany DTAA are taxable on receipt rather than accrual basis. Consideration for restricted, non-exclusive standard software licences that do not transfer copyright rights is not royalty under the Act or treaty. Separate scopes of work, invoicing, consideration and no profit-and-loss sharing prevent consortium members from constituting an association of persons; joint and several liability and indemnities alone are insufficient. Offshore equipment-supply income is not taxable in India merely because it forms part of a composite project. Transfer-pricing adjustments require a prescribed method and cannot rest on an ad hoc mark-up where transaction differences are reconciled and benchmarking is undisputed.
Royalty and fees for technical services under the India-Germany DTAA are taxable on receipt rather than accrual basis. Consideration for restricted, non-exclusive standard software licences that do not transfer copyright rights is not royalty under the Act or treaty. Separate scopes of work, invoicing, consideration and no profit-and-loss sharing prevent consortium members from constituting an association of persons; joint and several liability and indemnities alone are insufficient. Offshore equipment-supply income is not taxable in India merely because it forms part of a composite project. Transfer-pricing adjustments require a prescribed method and cannot rest on an ad hoc mark-up where transaction differences are reconciled and benchmarking is undisputed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4905