Embezzlement losses in charitable institutions remain allowable when misappropriation is established, irrecoverable, and not a specified-person benefi...
National long-distance undertaking status supports deduction where separately licensed infrastructure, resources, revenue, and expenditure establish c...
Agency reimbursement income follows contractual deposit-liability computation, while pending deposit collections do not constitute deemed-dividend loa...
Membership-consent thresholds for oppression petitions are satisfied by unchallenged voter-list consents, while unsupported forgery claims require pro...
Page of 4918
Press 'Enter' after typing page number.
761 to 780 of 98359 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
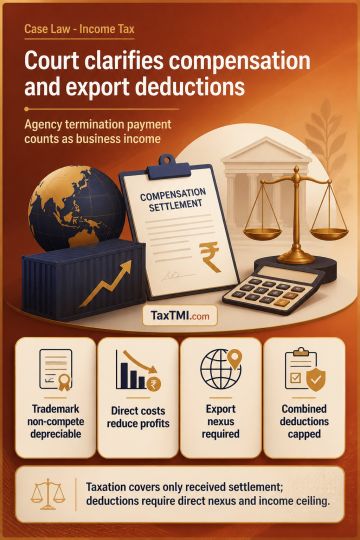
Termination compensation under a distribution arrangement that is substantively an agency relationship is treated as business income rather than a capital receipt, and taxation is confined to the settlement actually received. A non-compete covenant integral to acquiring and protecting a trademark qualifies as a depreciable intangible asset. For section 80-IB, only costs directly connected with an eligible undertaking should reduce its profit; allocation of finance, research, travel, head-office and export-promotion costs depends on factual nexus. Section 80HHC excludes receipts lacking a direct export nexus, while concurrent 80-IB and 80HHC deductions remain subject to the gross-total-income ceiling. A purely legal additional ground based on the existing record may be considered.
Termination compensation under a distribution arrangement that is substantively an agency relationship is treated as business income rather than a capital receipt, and taxation is confined to the settlement actually received. A non-compete covenant integral to acquiring and protecting a trademark qualifies as a depreciable intangible asset. For section 80-IB, only costs directly connected with an eligible undertaking should reduce its profit; allocation of finance, research, travel, head-office and export-promotion costs depends on factual nexus. Section 80HHC excludes receipts lacking a direct export nexus, while concurrent 80-IB and 80HHC deductions remain subject to the gross-total-income ceiling. A purely legal additional ground based on the existing record may be considered.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918