Compulsorily convertible debentures remain debt before conversion, preventing transfer-pricing and interest-deduction disallowances on the stated fact...
Stock-in-trade transfer taxability follows possession and consideration, not later conveyance registration, limiting deemed-value provisions to the ac...
Alternative statutory remedy under GST bars writ challenge where classification, notice variance, and hearing disputes require factual appellate revie...
Page of 4912
Press 'Enter' after typing page number.
541 to 560 of 98239 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
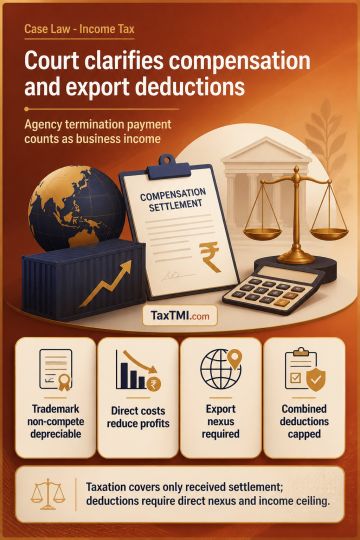
Termination compensation under a distribution arrangement that is substantively an agency relationship is treated as business income rather than a capital receipt, and taxation is confined to the settlement actually received. A non-compete covenant integral to acquiring and protecting a trademark qualifies as a depreciable intangible asset. For section 80-IB, only costs directly connected with an eligible undertaking should reduce its profit; allocation of finance, research, travel, head-office and export-promotion costs depends on factual nexus. Section 80HHC excludes receipts lacking a direct export nexus, while concurrent 80-IB and 80HHC deductions remain subject to the gross-total-income ceiling. A purely legal additional ground based on the existing record may be considered.
Termination compensation under a distribution arrangement that is substantively an agency relationship is treated as business income rather than a capital receipt, and taxation is confined to the settlement actually received. A non-compete covenant integral to acquiring and protecting a trademark qualifies as a depreciable intangible asset. For section 80-IB, only costs directly connected with an eligible undertaking should reduce its profit; allocation of finance, research, travel, head-office and export-promotion costs depends on factual nexus. Section 80HHC excludes receipts lacking a direct export nexus, while concurrent 80-IB and 80HHC deductions remain subject to the gross-total-income ceiling. A purely legal additional ground based on the existing record may be considered.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4912