Capital-gains exemption for charitable trusts extends to qualifying fixed deposits, while unrecoverable TDS write-offs may constitute income applicati...
India-UK treaty characterisation of telecom-service receipts as business profits withstands unilateral domestic-law amendments for Indian tax purposes...
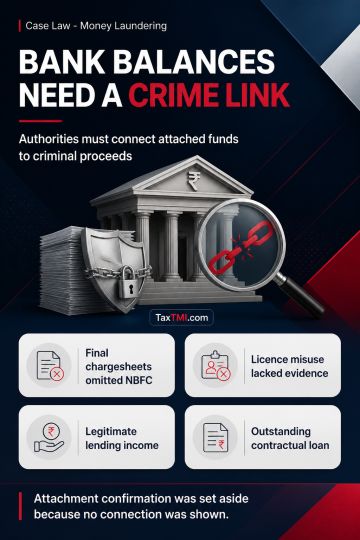
PMLA provisional attachment of an NBFC's bank balance requires material establishing that the property constitutes proceeds of crime connected with a scheduled offence. FIR allegations alone were insufficient where final chargesheets did not arraign the NBFC or its lending application, and no material showed that an unauthorised fintech operated under its licence or that the NBFC received identified criminal proceeds. Legitimate lending income and an outstanding contractual loan cannot be characterised as proceeds of crime without supporting evidence. As no nexus was identified between the attached balance and criminal proceeds, confirmation of the attachment was set aside.
PMLA provisional attachment of an NBFC's bank balance requires material establishing that the property constitutes proceeds of crime connected with a scheduled offence. FIR allegations alone were insufficient where final chargesheets did not arraign the NBFC or its lending application, and no material showed that an unauthorised fintech operated under its licence or that the NBFC received identified criminal proceeds. Legitimate lending income and an outstanding contractual loan cannot be characterised as proceeds of crime without supporting evidence. As no nexus was identified between the attached balance and criminal proceeds, confirmation of the attachment was set aside.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915