Constitutional personal-liberty safeguards limit PMLA twin bail conditions where completed investigations lead to prolonged incarceration before trial...
Automated airline software subscriptions without human intervention fail technical-services characterisation and do not make available underlying tech...
Page of 4925
Press 'Enter' after typing page number.
361 to 380 of 98491 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
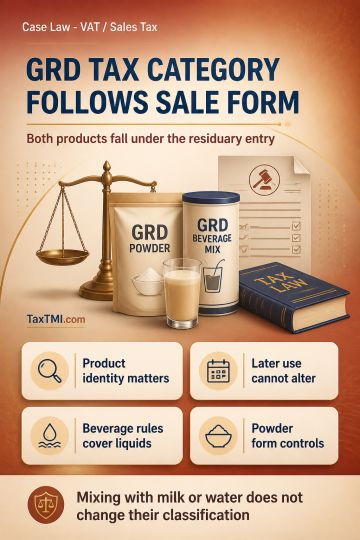
Tax classification of GRD Powder and GRD Mix depends on the goods' identity and physical form at the time of supply, not on their subsequent use after mixing with milk or water. Strict construction of taxing statutes requires classification at the taxable event; a purchaser's use cannot convert a powder or biscuit-form product into a beverage. The entry for non-alcoholic drinks and beverages, read ejusdem generis with syrups, cordials, distilled juices, ark and essences, covers liquids or liquid preparations. GRD Powder and GRD Mix therefore fall under the residuary entry rather than the specific entry for non-alcoholic drinks and beverages.
Tax classification of GRD Powder and GRD Mix depends on the goods' identity and physical form at the time of supply, not on their subsequent use after mixing with milk or water. Strict construction of taxing statutes requires classification at the taxable event; a purchaser's use cannot convert a powder or biscuit-form product into a beverage. The entry for non-alcoholic drinks and beverages, read ejusdem generis with syrups, cordials, distilled juices, ark and essences, covers liquids or liquid preparations. GRD Powder and GRD Mix therefore fall under the residuary entry rather than the specific entry for non-alcoholic drinks and beverages.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4925