Cross-segment derivatives manipulation: integrated order patterns can support interim restraints, while director liability requires responsibility, co...
Power bank definition limits the customs-duty exclusion, preserving concessional treatment for stationary, grid-scale and industrial battery storage s...
Packing-material input credits support inverted-duty refunds for packaged tea, while rate-reduction and concessional-supply circulars remain inapplica...
Page of 4908
Press 'Enter' after typing page number.
161 to 180 of 98141 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
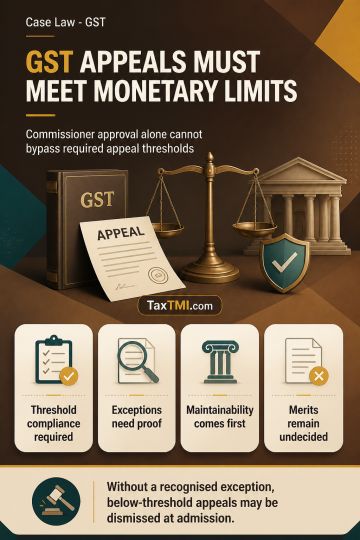
Monetary-limit compliance governs departmental GST appeals even where the Commissioner authorises an application under Section 112(3). Appeals below the prescribed threshold require the Revenue to specifically plead and establish a recognised exception under the applicable litigation-control framework. A bare assertion of the Commissioner's permission does not prove a residual exception without material demonstrating a case-specific recorded opinion. Maintainability must be determined before the underlying tax merits are considered. Where no recognised exception is established, a below-threshold departmental appeal is liable to dismissal at the admission stage, leaving the substantive tax dispute undecided.
Monetary-limit compliance governs departmental GST appeals even where the Commissioner authorises an application under Section 112(3). Appeals below the prescribed threshold require the Revenue to specifically plead and establish a recognised exception under the applicable litigation-control framework. A bare assertion of the Commissioner's permission does not prove a residual exception without material demonstrating a case-specific recorded opinion. Maintainability must be determined before the underlying tax merits are considered. Where no recognised exception is established, a below-threshold departmental appeal is liable to dismissal at the admission stage, leaving the substantive tax dispute undecided.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4908