Supervisory permanent establishment requires project-wise duration and qualifying construction nexus; offshore supplies and salary reimbursements rema...
Transfer-pricing comparability permits fresh objections and filters where software service comparables are functionally unsuitable for arm's-length pr...
Territorial rendering requirement excludes China-based management and consultancy services from fees for technical services under the India-China DTAA...
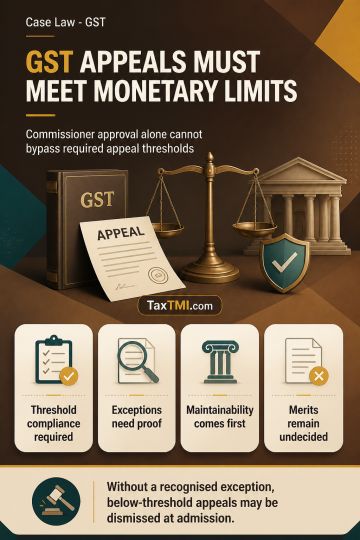
Monetary-limit compliance governs departmental GST appeals even where the Commissioner authorises an application under Section 112(3). Appeals below the prescribed threshold require the Revenue to specifically plead and establish a recognised exception under the applicable litigation-control framework. A bare assertion of the Commissioner's permission does not prove a residual exception without material demonstrating a case-specific recorded opinion. Maintainability must be determined before the underlying tax merits are considered. Where no recognised exception is established, a below-threshold departmental appeal is liable to dismissal at the admission stage, leaving the substantive tax dispute undecided.
Monetary-limit compliance governs departmental GST appeals even where the Commissioner authorises an application under Section 112(3). Appeals below the prescribed threshold require the Revenue to specifically plead and establish a recognised exception under the applicable litigation-control framework. A bare assertion of the Commissioner's permission does not prove a residual exception without material demonstrating a case-specific recorded opinion. Maintainability must be determined before the underlying tax merits are considered. Where no recognised exception is established, a below-threshold departmental appeal is liable to dismissal at the admission stage, leaving the substantive tax dispute undecided.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4913