Income Declaration Scheme declarations can evidence share-capital sources, while round-tripped funds and cash-linked credits require further verificat...
Permanent establishment tests: independent subsidiary premises and principal-to-principal dealings did not create Indian taxability for offshore suppl...
Valuation Officer estimates govern property-value additions once statutory valuation is invoked, requiring fresh consideration of objections and compa...
Waiver of written show-cause notice may prevent a later procedural challenge after participation in customs adjudication, preserving statutory appella...
Retrospective invalidity of ocean-freight IGST supports refunds despite non-party status and prior credit utilisation, subject to authorised appeal gr...
Additional evidence in departmental appeals may include show-cause-notice material without introducing a new case where it merely corroborates existin...
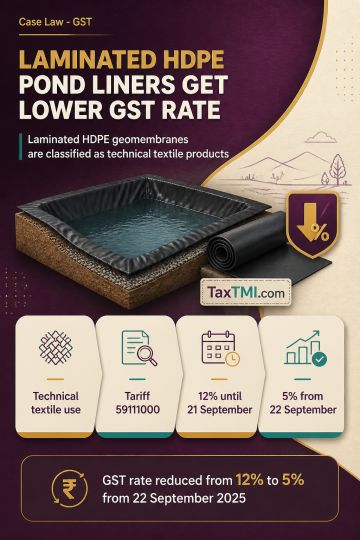
Laminated HDPE woven geomembrane used for waterproof pond lining, including Biofloc applications, is classified under tariff sub-heading 59111000 as a textile fabric for technical use. HDPE tapes and strips below 5 mm fall within Section XI, and their weaving produces textile fabric; lamination with plastic on both sides does not displace classification where the material serves a technical purpose under Chapter Note 8 to Chapter 59. The product attracted GST at 12 per cent up to 21 September 2025 and 5 per cent from 22 September 2025, following its placement under the relevant GST rate entries for tariff heading 5911.
Laminated HDPE woven geomembrane used for waterproof pond lining, including Biofloc applications, is classified under tariff sub-heading 59111000 as a textile fabric for technical use. HDPE tapes and strips below 5 mm fall within Section XI, and their weaving produces textile fabric; lamination with plastic on both sides does not displace classification where the material serves a technical purpose under Chapter Note 8 to Chapter 59. The product attracted GST at 12 per cent up to 21 September 2025 and 5 per cent from 22 September 2025, following its placement under the relevant GST rate entries for tariff heading 5911.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4905