Suspension of insolvency professional registration prevents continued Resolution Professional appointments and restricts interim stays that effectivel...
Original works exemption for railway contracts depends on actual integrated construction scope, while accessible tax data defeats suppression allegati...
Survey surrender characterisation determines whether mixed excess stock and business-linked cash face normal taxation or special deemed-income taxatio...
Page of 4908
Press 'Enter' after typing page number.
201 to 220 of 98141 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
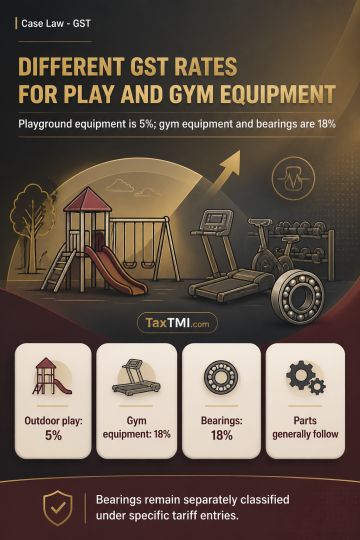
Outdoor playground equipment, including qualifying spare parts, is classified under tariff item 95069990 as sports goods and taxable at 5%. Outdoor gym equipment and its qualifying spare parts are classified under tariff item 95069190 as equipment for general physical exercise and taxable at 18%. Parts solely or principally used with Chapter 95 articles generally follow the equipment classification. Ball and roller bearings remain separately classifiable under Heading 8482 because that specific tariff entry prevails over the general parts classification; their applicable tariff entry depends on their specifications, and they are taxable at 18%.
Outdoor playground equipment, including qualifying spare parts, is classified under tariff item 95069990 as sports goods and taxable at 5%. Outdoor gym equipment and its qualifying spare parts are classified under tariff item 95069190 as equipment for general physical exercise and taxable at 18%. Parts solely or principally used with Chapter 95 articles generally follow the equipment classification. Ball and roller bearings remain separately classifiable under Heading 8482 because that specific tariff entry prevails over the general parts classification; their applicable tariff entry depends on their specifications, and they are taxable at 18%.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4908