Call-recording requirements for institutional-investor client communications become non-mandatory, while institutional-investor status adopts the exis...
Restricted silver imports may clear under a valid import authorisation without additional status or exchange-routing requirements unless expressly imp...
Head Office cost allocation requires prescribed transfer-pricing methods; treaty ceilings bar surcharge and cess, while duplicate taxation is excluded...
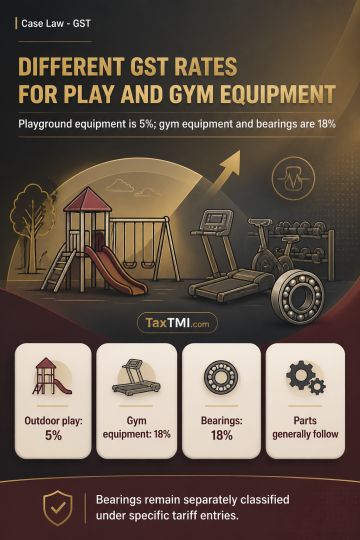
Outdoor playground equipment, including qualifying spare parts, is classified under tariff item 95069990 as sports goods and taxable at 5%. Outdoor gym equipment and its qualifying spare parts are classified under tariff item 95069190 as equipment for general physical exercise and taxable at 18%. Parts solely or principally used with Chapter 95 articles generally follow the equipment classification. Ball and roller bearings remain separately classifiable under Heading 8482 because that specific tariff entry prevails over the general parts classification; their applicable tariff entry depends on their specifications, and they are taxable at 18%.
Outdoor playground equipment, including qualifying spare parts, is classified under tariff item 95069990 as sports goods and taxable at 5%. Outdoor gym equipment and its qualifying spare parts are classified under tariff item 95069190 as equipment for general physical exercise and taxable at 18%. Parts solely or principally used with Chapter 95 articles generally follow the equipment classification. Ball and roller bearings remain separately classifiable under Heading 8482 because that specific tariff entry prevails over the general parts classification; their applicable tariff entry depends on their specifications, and they are taxable at 18%.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI