Compulsorily convertible debentures remain debt before conversion, preventing transfer-pricing and interest-deduction disallowances on the stated fact...
Stock-in-trade transfer taxability follows possession and consideration, not later conveyance registration, limiting deemed-value provisions to the ac...
Alternative statutory remedy under GST bars writ challenge where classification, notice variance, and hearing disputes require factual appellate revie...
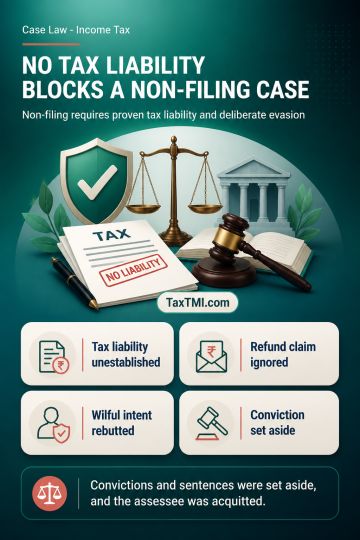
Tax payable is material to prosecution for failure to furnish a return under Section 276CC because the statutory exception depends on the assessee's tax liability. Where no assessment or other tax determination exists, the complaint does not allege tax payable, and a refund claim remains unaddressed, prosecution is misconceived. Wilful failure is also essential: the statutory presumption of culpable mental state may be rebutted through evidence showing no intent to evade tax. Evidence that property was jointly acquired, loan-financed, and that sale consideration was received by the spouse rebutted wilfulness. The convictions and sentences were set aside, and the assessee was acquitted.
Tax payable is material to prosecution for failure to furnish a return under Section 276CC because the statutory exception depends on the assessee's tax liability. Where no assessment or other tax determination exists, the complaint does not allege tax payable, and a refund claim remains unaddressed, prosecution is misconceived. Wilful failure is also essential: the statutory presumption of culpable mental state may be rebutted through evidence showing no intent to evade tax. Evidence that property was jointly acquired, loan-financed, and that sale consideration was received by the spouse rebutted wilfulness. The convictions and sentences were set aside, and the assessee was acquitted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4907