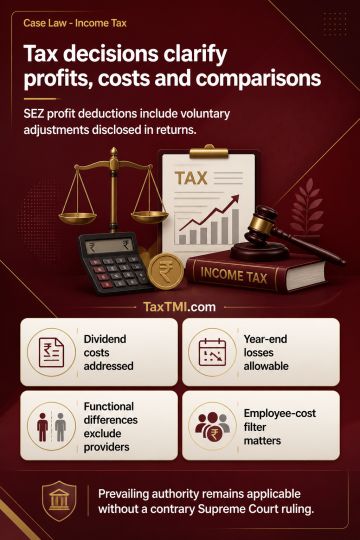
SEZ-unit profit deduction covers voluntary transfer-pricing adjustments, while exempt-income costs, foreign-exchange loss and ITeS comparables are exa...
Infrastructure-development deduction remains available to EPC contractors when substantive statutory conditions outweigh contractor labels in agreemen...
Explained Investment Sources: documented gifts and traceable salary savings supported deletion of additions for property and mutual-fund SIP investmen...
Internal comparable pricing supports arm's-length interest on compulsorily convertible debentures, preventing their recharacterisation as equity for t...
Page of 4921
Press 'Enter' after typing page number.
981 to 1000 of 98411 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
Section 129 transit penalties may operate on a strict-liability basis, but still require proof of a statutory breach attracting the penalty. Where invoices, e-way bills and bilty documents matched the goods, the buyer was identifiable, and historical records supported use of its former address, a repeated consignee-address entry was treated as a bona fide documentary error. In the absence of evidence of a fictitious purchaser, diversion, clandestine unloading, value suppression, or tax evasion, the discrepancy did not establish a substantive transit violation. The transit penalty and consequential recovery were annulled, while tax lawfully payable on the supply remained unaffected.
Section 129 transit penalties may operate on a strict-liability basis, but still require proof of a statutory breach attracting the penalty. Where invoices, e-way bills and bilty documents matched the goods, the buyer was identifiable, and historical records supported use of its former address, a repeated consignee-address entry was treated as a bona fide documentary error. In the absence of evidence of a fictitious purchaser, diversion, clandestine unloading, value suppression, or tax evasion, the discrepancy did not establish a substantive transit violation. The transit penalty and consequential recovery were annulled, while tax lawfully payable on the supply remained unaffected.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4921