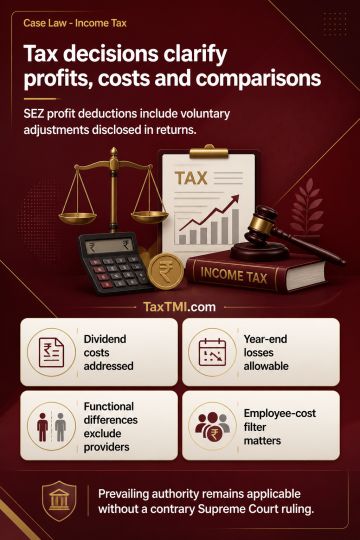
SEZ-unit profit deduction covers voluntary transfer-pricing adjustments, while exempt-income costs, foreign-exchange loss and ITeS comparables are exa...
GST refund disclosure in a tax audit report does not, by itself, establish taxable income. GST is a statutory levy collected and paid on behalf of the Government, and its refund represents a return of tax paid rather than income. Where refunded GST or IGST was not claimed as expenditure in the profit and loss account, it cannot be taxed solely because of its disclosure in the tax audit report. Allowability of the refund remains subject to examination of supporting records and applicable law.
GST refund disclosure in a tax audit report does not, by itself, establish taxable income. GST is a statutory levy collected and paid on behalf of the Government, and its refund represents a return of tax paid rather than income. Where refunded GST or IGST was not claimed as expenditure in the profit and loss account, it cannot be taxed solely because of its disclosure in the tax audit report. Allowability of the refund remains subject to examination of supporting records and applicable law.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918