Transfer-pricing comparability permits fresh objections and filters where software service comparables are functionally unsuitable for arm's-length pr...
Territorial rendering requirement excludes China-based management and consultancy services from fees for technical services under the India-China DTAA...
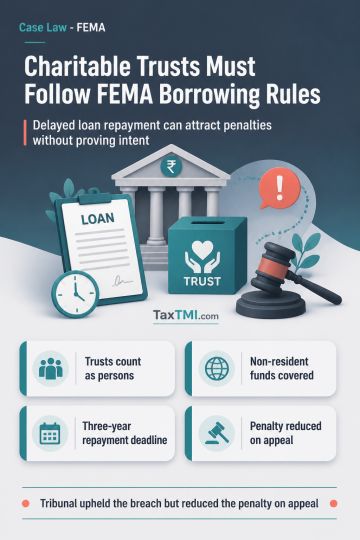
FEMA borrowing restrictions bind charitable trusts, and civil penalties apply without proving intent for delayed repayment of non-resident rupee loans...
GST refund disclosure in a tax audit report does not, by itself, establish taxable income. GST is a statutory levy collected and paid on behalf of the Government, and its refund represents a return of tax paid rather than income. Where refunded GST or IGST was not claimed as expenditure in the profit and loss account, it cannot be taxed solely because of its disclosure in the tax audit report. Allowability of the refund remains subject to examination of supporting records and applicable law.
GST refund disclosure in a tax audit report does not, by itself, establish taxable income. GST is a statutory levy collected and paid on behalf of the Government, and its refund represents a return of tax paid rather than income. Where refunded GST or IGST was not claimed as expenditure in the profit and loss account, it cannot be taxed solely because of its disclosure in the tax audit report. Allowability of the refund remains subject to examination of supporting records and applicable law.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916