Capital-gains exemption for charitable trusts extends to qualifying fixed deposits, while unrecoverable TDS write-offs may constitute income applicati...
India-UK treaty characterisation of telecom-service receipts as business profits withstands unilateral domestic-law amendments for Indian tax purposes...
Transfer-pricing reimbursement adjustments require uncontrolled comparables and cannot become expense-genuineness reviews, resulting in deletion of th...
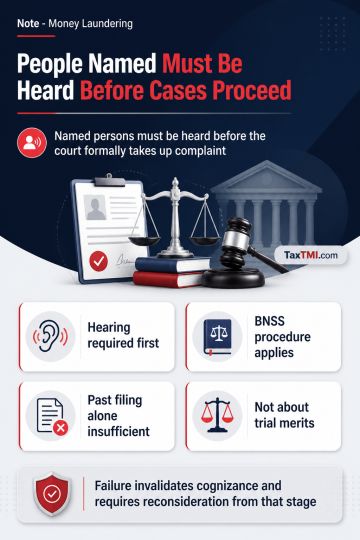
Section 223(1) BNSS requires a proposed accused to be heard before cognizance of a PMLA complaint where the BNSS governs the cognizance stage. Section 44(1)(b) PMLA permits direct cognizance without committal but does not displace incorporated complaint safeguards; Sections 46 and 65 preserve criminal procedure unless inconsistent with the PMLA. Section 71 operates only upon inconsistency. Registration or listing of a complaint before BNSS commencement is administrative, not a pending inquiry under the saving clause, absent judicial application of mind. Non-compliance with the hearing requirement renders cognizance invalid and requires reconsideration from that stage; the hearing addresses prima facie cognizance, not trial merits.
Section 223(1) BNSS requires a proposed accused to be heard before cognizance of a PMLA complaint where the BNSS governs the cognizance stage. Section 44(1)(b) PMLA permits direct cognizance without committal but does not displace incorporated complaint safeguards; Sections 46 and 65 preserve criminal procedure unless inconsistent with the PMLA. Section 71 operates only upon inconsistency. Registration or listing of a complaint before BNSS commencement is administrative, not a pending inquiry under the saving clause, absent judicial application of mind. Non-compliance with the hearing requirement renders cognizance invalid and requires reconsideration from that stage; the hearing addresses prima facie cognizance, not trial merits.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915