Membership-consent thresholds for oppression petitions are satisfied by unchallenged voter-list consents, while unsupported forgery claims require pro...
Juridical seat versus arbitral venue determines supervisory court jurisdiction, while timely award challenges remain within the prescribed limitation ...
Page of 4915
Press 'Enter' after typing page number.
701 to 720 of 98288 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
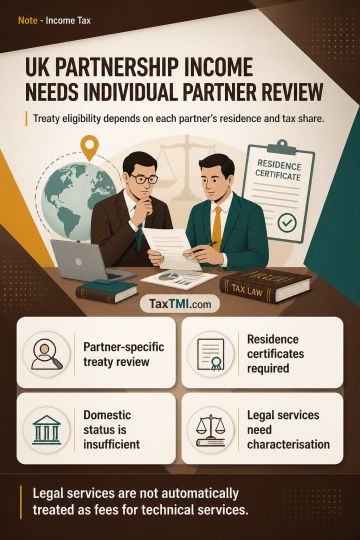
Fiscal transparency of a UK partnership requires Indian-source income to be tested partner by partner for treaty entitlement. Article 4(1)(b) of the India-UK DTAA limits protection to the share taxed as income of a UK resident, whether in the partnership's or partners' hands; it does not bar non-UK resident partners from invoking India's treaty with their own residence State. Domestic recognition of the partnership does not establish a single treaty residence. Treaty claims require residence certificates and prescribed information. Legal-professional services are not automatically fees for technical services merely because India-UK treaty relief is unavailable; their characterisation must satisfy domestic law and the applicable treaty's income article, including relevant fixed-base, permanent-establishment, or presence conditions.
Fiscal transparency of a UK partnership requires Indian-source income to be tested partner by partner for treaty entitlement. Article 4(1)(b) of the India-UK DTAA limits protection to the share taxed as income of a UK resident, whether in the partnership's or partners' hands; it does not bar non-UK resident partners from invoking India's treaty with their own residence State. Domestic recognition of the partnership does not establish a single treaty residence. Treaty claims require residence certificates and prescribed information. Legal-professional services are not automatically fees for technical services merely because India-UK treaty relief is unavailable; their characterisation must satisfy domestic law and the applicable treaty's income article, including relevant fixed-base, permanent-establishment, or presence conditions.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915