Business support recruitment and training receipts qualify for presumptive business taxation, not professional taxation under technical consultancy ru...
Treaty exemption for foreign permanent-establishment management fees prevailed, while dividend expense disallowance remained limited to an accepted al...
Centralised assessment transfers: participation after requesting centralisation can bar technical jurisdictional challenges, while assessment disputes...
Binding precedent remains operative despite pending challenge, supporting deletion of interest disallowance when debt is converted into preference sha...
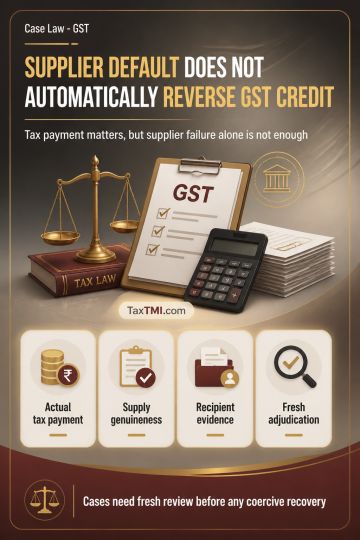
Section 16(2)(c) makes actual payment of tax by the supplier a foundational condition for input tax credit and is constitutionally valid. Credit cannot, however, be denied mechanically merely because a supplier's registration was cancelled or its returns show nil or short tax liability. Adjudication must assess the genuineness of supply, recipient evidence, circumstances of supplier default, available recovery action against the supplier, and the applicable statutory framework. Proceedings under Section 74 must state the foundational facts establishing fraud, wilful misstatement or suppression by the recipient; supplier fraud cannot be attributed without a direct factual link. Pending and concluded matters require fresh adjudication or reconsideration with hearing and without coercive recovery until determination.
Section 16(2)(c) makes actual payment of tax by the supplier a foundational condition for input tax credit and is constitutionally valid. Credit cannot, however, be denied mechanically merely because a supplier's registration was cancelled or its returns show nil or short tax liability. Adjudication must assess the genuineness of supply, recipient evidence, circumstances of supplier default, available recovery action against the supplier, and the applicable statutory framework. Proceedings under Section 74 must state the foundational facts establishing fraud, wilful misstatement or suppression by the recipient; supplier fraud cannot be attributed without a direct factual link. Pending and concluded matters require fresh adjudication or reconsideration with hearing and without coercive recovery until determination.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4913