Loading...

⚠ ✕
❮ Top
☎ Help
☰
×

By creating an account you can:

Logo TaxTMI
Call Us / Help / Feedback✕

Contact Us At :

✉ E-mail: [email protected]

✆ Call / WhatsApp at: +91 99117 96707

For more information, Check Contact Us

FAQs :

To know Frequently Asked Questions, Check FAQs

Most Asked Video Tutorials :

For more tutorials, Check Video Tutorials

Submit Feedback/Suggestion :

Email :
Please provide your email address so we can follow up on your feedback.
Category :
Description :
Min 15 characters 0/2000
Make Most of Text Search ✕
  1. Checkout this video tutorial: How to search effectively on TaxTMI.
  2. Put words in double quotes for exact word search, eg: "income tax"
  3. Avoid noise words such as : 'and, of, the, a'
  4. Sort by Relevance to get the most relevant document.
  5. Press Enter to add multiple terms/multiple phrases, and then click on Search to Search.
  6. Text Search
  7. The system will try to fetch results that contains ALL your words.
  8. Once you add keywords, you'll see a new 'Search In' filter that makes your results even more precise.
  9. Text Search
╳
Add to...
You have not created any category. Kindly create one to bookmark this item!
✕
Create New Category
Hide
Title :
Description :
❮❮ Hide
❮ Default View
Expand ❯❯
Close ✕
🔎 Filters / Advanced Search ❯
TEXT

Press 'Enter' to add multiple search terms. Rules for Better Search

Search In
Main Text + AI Text ❯
  • Main Text
  • Main Text + AI Text
  • AI Text
Law:
---- All Laws---- ❯
  • ---- All Laws----
  • Income Tax
  • Direct Taxes
  • Benami Property
  • Central GST Laws
  • SGST - State GST Laws
  • Customs
  • FTP - Foreign Trade Policy
  • SEZ - Special Economic Zone
  • FEMA - Foreign Exchange Management
  • Companies Law
  • SEBI - Securities & Exchange Board of India
  • IBC - Insolvency and Bankruptcy
  • Law of Competition
  • PMLA - Money-Laundering
  • Indian Laws
  • Bill / Finance Bills
  • Wealth Tax
  • Service Tax
  • Central Excise
  • VAT / Sales Tax
Month:
---- All Months ---- ❯
  • ---- All Months ----
  • January
  • February
  • March
  • April
  • May
  • June
  • July
  • August
  • September
  • October
  • November
  • December
Year:
---- All Years ---- ❯
  • ---- All Years ----
  • 2026
  • 2025
  • 2024
  • 2023
  • 2022
  • 2021
  • 2020
  • 2019
  • 2018
  • 2017
  • 2016
  • 2015
  • 2014
  • 2013
  • 2012
  • 2011
Sort By: ?
In Sort By 'Default', exact matches for text search are shown at the top, followed by the remaining results in their regular order.
Relevance Default Date
☰   Show Results ❯
    Foreign LTC tax treatment requires TDS on known non-exempt travel claims despite recovery-related interim relief.
    Extended GST limitation requires a notice to plead fraud, wilful misstatement or suppression with supporting factual particulars.
    Merchant banker appointment exemption permits eligible regulated listed issuers to privately place highly rated debt without appointing one.
    Reassignment of pending legacy indirect-tax appeals directs listed matters to designated appellate Commissioners for Orders-in-Appeal.
    Export Declaration Form authentication at Non-EDI Customs locations requires secure electronic forwarding to the designated Authorised Dealer.
    Customs area declaration enables O Yard CFS to handle Kamarajar Port import, baggage and export cargo under prescribed procedures.
    Customs custody appointment extends O Yard CFS responsibility to imports and exports routed through Kamarajar Port.
    Electronic GST authentication validates portal-issued demand notices, while portal upload starts limitation and RFN can replace DIN.
    Assessment of unregistered persons must precede GST recovery proceedings, leaving educational institution exemption claims open for determination.
    Revised customs prosecution thresholds can govern pending gold-smuggling complaints, requiring reconsideration of withdrawal despite prior prosecution...
    Leasehold rights assignments in industrial plots remain outside GST where treated as benefits arising from immovable property.
    Pre-deposit timing turns on final acknowledgement, allowing a timely defect cure before appeal registration and merits consideration.
    Proportionality review restricts reduction of FERA penalties unless the sanction is grossly excessive, unduly harsh, or conscience-shocking.
    Offshore supply receipts remain outside Indian taxation where CIF title passes abroad and contracts are genuinely separate.
    Income Declaration Scheme declarations can evidence share-capital sources, while round-tripped funds and cash-linked credits require further verificat...
    Business set-up versus commencement determines deductibility, while appellate findings require consideration of contemporaneous operational evidence.
    Mandatory GST credit reversal on unsold completed units becomes deductible project cost when final allocation crystallises.
    Permanent establishment tests: independent subsidiary premises and principal-to-principal dealings did not create Indian taxability for offshore suppl...
    Electronic receipt of DRP directions triggers the final-assessment deadline, rendering delayed faceless assessments time-barred and invalid.
    Gifted share holding periods include prior ownership, but indexation begins only when the donee's deemed cost is taxed.
❮
❯
❯❯
Maximize Maximize Maximize
0 / 200
Expand Note
Add to Folder

No Folders have been created

+

Are you sure you want to delete "My most important" ?

NOTE:

Highlights
Showing Results for :
Reset Filters
Results Found:
Show All Summaries Hide All Summaries

Highlights

Back

All Highlights

Showing Results for :
Reset Filters
No Records Found

Highlights

Back

All Highlights

Section 16(2)(c) makes actual payment of tax by the supplier a...

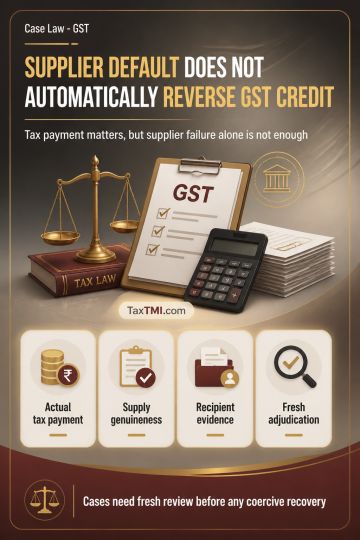
Input tax credit conditions require actual tax payment, but supplier default alone cannot justify mechanical credit reversal.

Contents
Summary
Note

Note

-

Bookmark

Print

Print

GST October 5, 2026 Case Laws HC
Section 16(2)(c) makes actual payment of tax by the supplier a foundational condition for input tax credit and is constitutionally valid. Credit cannot, however, be denied mechanically merely because a supplier's registration was cancelled or its returns show nil or short tax liability. Adjudication must assess the genuineness of supply, recipient evidence, circumstances of supplier default, available recovery action against the supplier, and the applicable statutory framework. Proceedings under Section 74 must state the foundational facts establishing fraud, wilful misstatement or suppression by the recipient; supplier fraud cannot be attributed without a direct factual link. Pending and concluded matters require fresh adjudication or reconsideration with hearing and without coercive recovery until determination.

Topics

Acts Income Tax