Split consignment classification treated complementary motorcycle parts as one imported motorcycle, sustaining valuation, confiscation and importer li...
Timely pronouncement of reserved judgments requires defined timelines, transparency measures, and remedial pathways to protect liberty and effective j...
Settlement-price depression requires proof of manipulation, not merely short exposure, late selling, or below-market orders, preserving disclosure pen...
Page of 4907
Press 'Enter' after typing page number.
301 to 320 of 98136 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
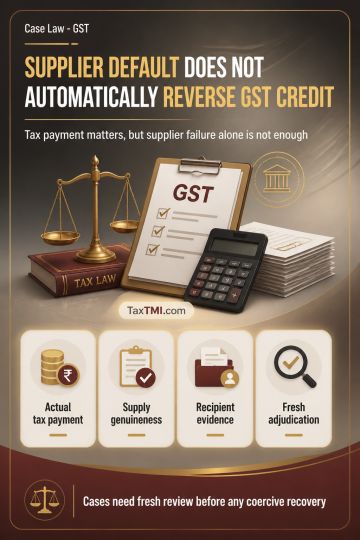
Section 16(2)(c) makes actual payment of tax by the supplier a foundational condition for input tax credit and is constitutionally valid. Credit cannot, however, be denied mechanically merely because a supplier's registration was cancelled or its returns show nil or short tax liability. Adjudication must assess the genuineness of supply, recipient evidence, circumstances of supplier default, available recovery action against the supplier, and the applicable statutory framework. Proceedings under Section 74 must state the foundational facts establishing fraud, wilful misstatement or suppression by the recipient; supplier fraud cannot be attributed without a direct factual link. Pending and concluded matters require fresh adjudication or reconsideration with hearing and without coercive recovery until determination.
Section 16(2)(c) makes actual payment of tax by the supplier a foundational condition for input tax credit and is constitutionally valid. Credit cannot, however, be denied mechanically merely because a supplier's registration was cancelled or its returns show nil or short tax liability. Adjudication must assess the genuineness of supply, recipient evidence, circumstances of supplier default, available recovery action against the supplier, and the applicable statutory framework. Proceedings under Section 74 must state the foundational facts establishing fraud, wilful misstatement or suppression by the recipient; supplier fraud cannot be attributed without a direct factual link. Pending and concluded matters require fresh adjudication or reconsideration with hearing and without coercive recovery until determination.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4907