Compulsorily convertible debentures remain debt before conversion, preventing transfer-pricing and interest-deduction disallowances on the stated fact...
Stock-in-trade transfer taxability follows possession and consideration, not later conveyance registration, limiting deemed-value provisions to the ac...
Alternative statutory remedy under GST bars writ challenge where classification, notice variance, and hearing disputes require factual appellate revie...
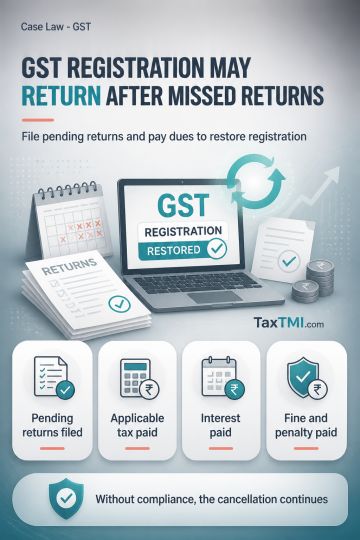
GST registration cancelled solely for non-filing of returns may be restored conditionally, since continued cancellation prevents invoicing and business operations and may hinder tax recovery. Restoration requires filing all pending returns and paying applicable tax, interest, fine and penalty within the stipulated period. Compliance enables restoration and permits final determination of tax liability through filed returns; non-compliance results in cancellation continuing.
GST registration cancelled solely for non-filing of returns may be restored conditionally, since continued cancellation prevents invoicing and business operations and may hinder tax recovery. Restoration requires filing all pending returns and paying applicable tax, interest, fine and penalty within the stipulated period. Compliance enables restoration and permits final determination of tax liability through filed returns; non-compliance results in cancellation continuing.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4907