Clubbing of income from gifted property failed where the claim surfaced after reassessment limitation, sustaining capital-gains assessment in spouse's...
Employee stock-option discount qualifies as revenue expenditure, while royalty and service comparables require reliable functional and transactional b...
Special insurance income computation preserves statutory deductions while limiting transfer-pricing, withholding and disallowance adjustments for gene...
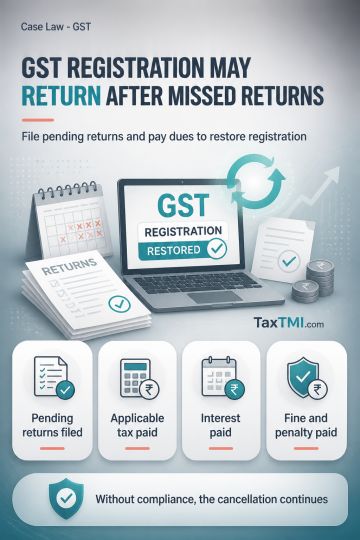
GST registration cancelled solely for non-filing of returns may be restored conditionally, since continued cancellation prevents invoicing and business operations and may hinder tax recovery. Restoration requires filing all pending returns and paying applicable tax, interest, fine and penalty within the stipulated period. Compliance enables restoration and permits final determination of tax liability through filed returns; non-compliance results in cancellation continuing.
GST registration cancelled solely for non-filing of returns may be restored conditionally, since continued cancellation prevents invoicing and business operations and may hinder tax recovery. Restoration requires filing all pending returns and paying applicable tax, interest, fine and penalty within the stipulated period. Compliance enables restoration and permits final determination of tax liability through filed returns; non-compliance results in cancellation continuing.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4910