Suspension of insolvency professional registration prevents continued Resolution Professional appointments and restricts interim stays that effectivel...
Original works exemption for railway contracts depends on actual integrated construction scope, while accessible tax data defeats suppression allegati...
Survey surrender characterisation determines whether mixed excess stock and business-linked cash face normal taxation or special deemed-income taxatio...
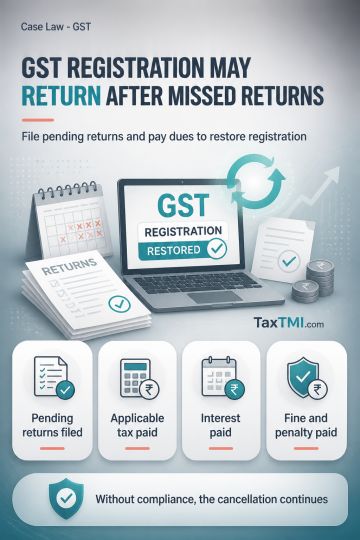
GST registration cancelled solely for non-filing of returns may be restored conditionally, since continued cancellation prevents invoicing and business operations and may hinder tax recovery. Restoration requires filing all pending returns and paying applicable tax, interest, fine and penalty within the stipulated period. Compliance enables restoration and permits final determination of tax liability through filed returns; non-compliance results in cancellation continuing.
GST registration cancelled solely for non-filing of returns may be restored conditionally, since continued cancellation prevents invoicing and business operations and may hinder tax recovery. Restoration requires filing all pending returns and paying applicable tax, interest, fine and penalty within the stipulated period. Compliance enables restoration and permits final determination of tax liability through filed returns; non-compliance results in cancellation continuing.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4910