Income Declaration Scheme declarations can evidence share-capital sources, while round-tripped funds and cash-linked credits require further verificat...
Permanent establishment tests: independent subsidiary premises and principal-to-principal dealings did not create Indian taxability for offshore suppl...
Valuation Officer estimates govern property-value additions once statutory valuation is invoked, requiring fresh consideration of objections and compa...
Waiver of written show-cause notice may prevent a later procedural challenge after participation in customs adjudication, preserving statutory appella...
Page of 4905
Press 'Enter' after typing page number.
321 to 340 of 98083 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
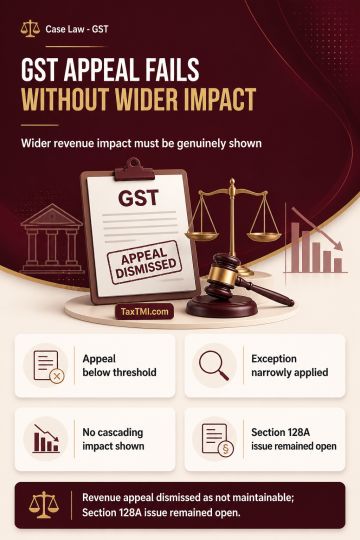
Board monetary-limit litigation policy permits a departmental GST appeal below the prescribed threshold only where a stated exclusion applies. The recurring-issue or interpretation exclusion requires genuine recurring or wider revenue implications; it does not cover every interpretative dispute, mere disagreement with an appellate order, or a general need to construe a provision. As no recurring or cascading implication was pleaded or established, the Revenue appeal against penalty deletion following Section 128A relief was dismissed as not maintainable. Whether that relief could be granted without the prescribed application remained open.
Board monetary-limit litigation policy permits a departmental GST appeal below the prescribed threshold only where a stated exclusion applies. The recurring-issue or interpretation exclusion requires genuine recurring or wider revenue implications; it does not cover every interpretative dispute, mere disagreement with an appellate order, or a general need to construe a provision. As no recurring or cascading implication was pleaded or established, the Revenue appeal against penalty deletion following Section 128A relief was dismissed as not maintainable. Whether that relief could be granted without the prescribed application remained open.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4905