Split consignment classification treated complementary motorcycle parts as one imported motorcycle, sustaining valuation, confiscation and importer li...
Timely pronouncement of reserved judgments requires defined timelines, transparency measures, and remedial pathways to protect liberty and effective j...
Settlement-price depression requires proof of manipulation, not merely short exposure, late selling, or below-market orders, preserving disclosure pen...
Page of 4907
Press 'Enter' after typing page number.
301 to 320 of 98136 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
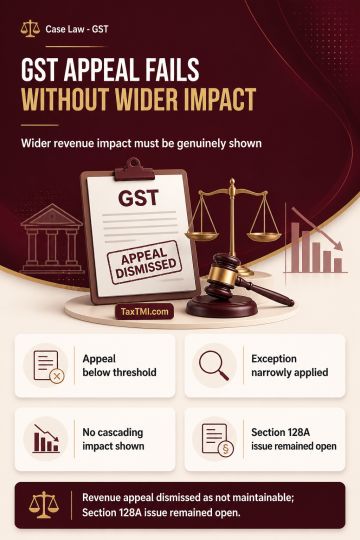
Board monetary-limit litigation policy permits a departmental GST appeal below the prescribed threshold only where a stated exclusion applies. The recurring-issue or interpretation exclusion requires genuine recurring or wider revenue implications; it does not cover every interpretative dispute, mere disagreement with an appellate order, or a general need to construe a provision. As no recurring or cascading implication was pleaded or established, the Revenue appeal against penalty deletion following Section 128A relief was dismissed as not maintainable. Whether that relief could be granted without the prescribed application remained open.
Board monetary-limit litigation policy permits a departmental GST appeal below the prescribed threshold only where a stated exclusion applies. The recurring-issue or interpretation exclusion requires genuine recurring or wider revenue implications; it does not cover every interpretative dispute, mere disagreement with an appellate order, or a general need to construe a provision. As no recurring or cascading implication was pleaded or established, the Revenue appeal against penalty deletion following Section 128A relief was dismissed as not maintainable. Whether that relief could be granted without the prescribed application remained open.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4907