Supervisory permanent establishment requires project-wise duration and qualifying construction nexus; offshore supplies and salary reimbursements rema...
Page of 4916
Press 'Enter' after typing page number.
821 to 840 of 98302 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
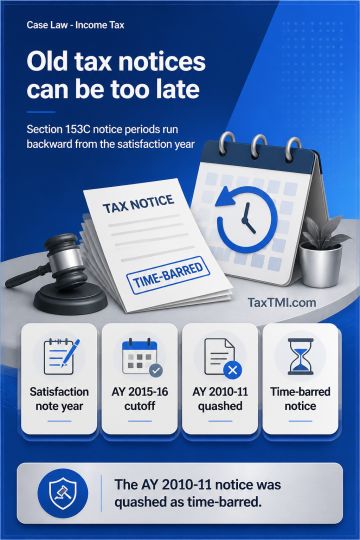
Limitation for notices under Sections 153A and 153C is reckoned backward from the assessment year in which the satisfaction note is recorded. Where the note was recorded in AY 2024-25, the stated extended limitation reached only AY 2015-16. A notice for AY 2010-11 therefore fell outside the permissible period and was quashed as time-barred.
Limitation for notices under Sections 153A and 153C is reckoned backward from the assessment year in which the satisfaction note is recorded. Where the note was recorded in AY 2024-25, the stated extended limitation reached only AY 2015-16. A notice for AY 2010-11 therefore fell outside the permissible period and was quashed as time-barred.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916