Revisional jurisdiction over export quota premium deductions requires both error and Revenue prejudice; a permissible assessment view cannot be displa...
Final benami adjudication bars contradictory tax-evasion prosecution where settlement findings confirm full disclosure and cooperation without conceal...
Faceless assessment and registration procedures are updated through electronic communication, revised recovery rules, extended deadlines, and replacem...
Risk-based selective vessel boarding requires accurate declarations and preserves master and agent liability where physical inspections are not select...
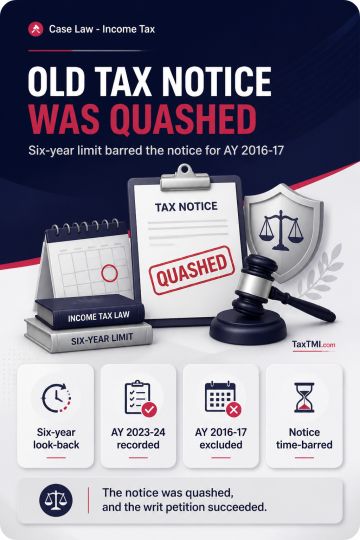
Section 153C limitation requires the six-year look-back period to be calculated from the assessment year immediately preceding the year in which the satisfaction note is recorded. Where the satisfaction note was recorded in AY 2023-24, the period extended only to AY 2017-18; AY 2016-17 lay outside it. The notice for AY 2016-17 was therefore time-barred and quashed, and the writ petition succeeded.
Note: It is a system-generated summary and is for quick reference only.