Arbitration of SEZ sub-lease monetary claims preserves rent, maintenance, termination, improvements and damages disputes while unused premises are vac...
Scientific research approval grants a research association tax recognition, subject to annual donor reporting, certification, and regulatory complianc...
Judicial discipline requires consistent reassessment treatment where identical facts were decided for the same taxpayer in the preceding assessment ye...
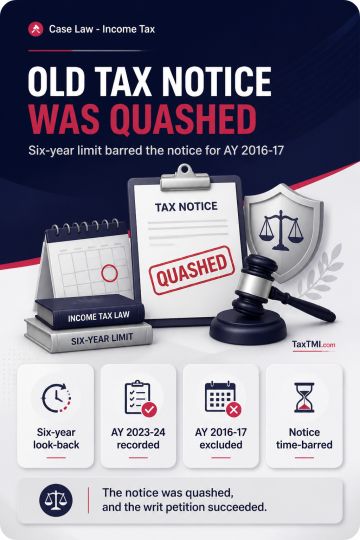
Section 153C limitation requires the six-year look-back period to be calculated from the assessment year immediately preceding the year in which the satisfaction note is recorded. Where the satisfaction note was recorded in AY 2023-24, the period extended only to AY 2017-18; AY 2016-17 lay outside it. The notice for AY 2016-17 was therefore time-barred and quashed, and the writ petition succeeded.
Note: It is a system-generated summary and is for quick reference only.