Delayed judgment pronouncement alone does not invalidate Tribunal orders, while rectification cannot reopen evidence or negate confiscation-related pe...
Agricultural-land reinvestment qualifies when transfer consideration precedes replacement purchase, while unexamined claims may be reassessed on escap...
Bona fide public fixed-deposit explanations prevent concealment penalties where unexplained-credit additions lack independent evidence of undisclosed ...
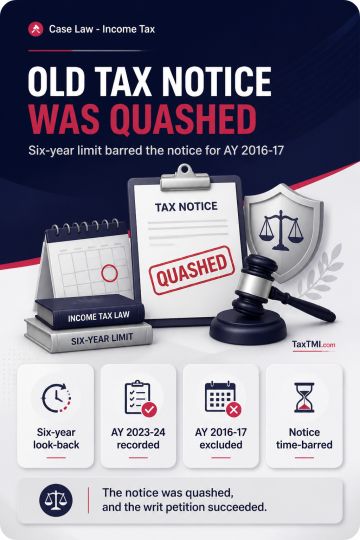
Section 153C limitation requires the six-year look-back period to be calculated from the assessment year immediately preceding the year in which the satisfaction note is recorded. Where the satisfaction note was recorded in AY 2023-24, the period extended only to AY 2017-18; AY 2016-17 lay outside it. The notice for AY 2016-17 was therefore time-barred and quashed, and the writ petition succeeded.
Note: It is a system-generated summary and is for quick reference only.