Arbitration of SEZ sub-lease monetary claims preserves rent, maintenance, termination, improvements and damages disputes while unused premises are vac...
Scientific research approval grants a research association tax recognition, subject to annual donor reporting, certification, and regulatory complianc...
Judicial discipline requires consistent reassessment treatment where identical facts were decided for the same taxpayer in the preceding assessment ye...
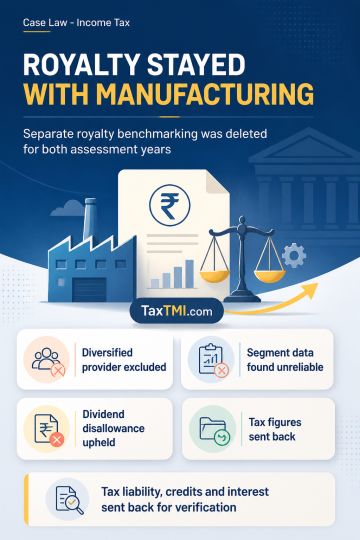
Transfer-pricing benchmarking under TNMM required royalty for engine technology to remain aggregated with the manufacturing segment once TNMM had been accepted as the most appropriate method; separate royalty benchmarking was deleted for both assessment years. Engineering and design comparability required exclusion of a company with diversified services, no reliable segmental data, a different functional profile and an extraordinary acquisition; margins require recomputation. The expenditure disallowance relating to exempt dividend income was sustained under section 14A read with Rule 8D. Tax liability, credits and interest computations were remitted for verification and correction.
Transfer-pricing benchmarking under TNMM required royalty for engine technology to remain aggregated with the manufacturing segment once TNMM had been accepted as the most appropriate method; separate royalty benchmarking was deleted for both assessment years. Engineering and design comparability required exclusion of a company with diversified services, no reliable segmental data, a different functional profile and an extraordinary acquisition; margins require recomputation. The expenditure disallowance relating to exempt dividend income was sustained under section 14A read with Rule 8D. Tax liability, credits and interest computations were remitted for verification and correction.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4905