Delayed judgment pronouncement alone does not invalidate Tribunal orders, while rectification cannot reopen evidence or negate confiscation-related pe...
Agricultural-land reinvestment qualifies when transfer consideration precedes replacement purchase, while unexamined claims may be reassessed on escap...
Bona fide public fixed-deposit explanations prevent concealment penalties where unexplained-credit additions lack independent evidence of undisclosed ...
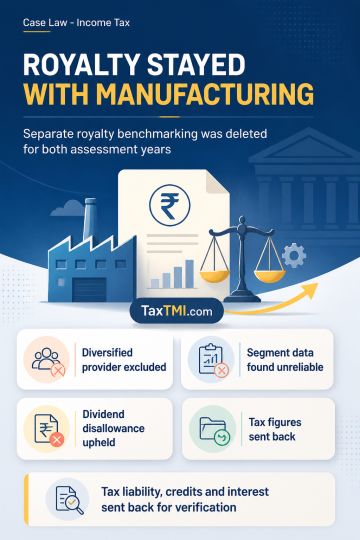
Transfer-pricing benchmarking under TNMM required royalty for engine technology to remain aggregated with the manufacturing segment once TNMM had been accepted as the most appropriate method; separate royalty benchmarking was deleted for both assessment years. Engineering and design comparability required exclusion of a company with diversified services, no reliable segmental data, a different functional profile and an extraordinary acquisition; margins require recomputation. The expenditure disallowance relating to exempt dividend income was sustained under section 14A read with Rule 8D. Tax liability, credits and interest computations were remitted for verification and correction.
Transfer-pricing benchmarking under TNMM required royalty for engine technology to remain aggregated with the manufacturing segment once TNMM had been accepted as the most appropriate method; separate royalty benchmarking was deleted for both assessment years. Engineering and design comparability required exclusion of a company with diversified services, no reliable segmental data, a different functional profile and an extraordinary acquisition; margins require recomputation. The expenditure disallowance relating to exempt dividend income was sustained under section 14A read with Rule 8D. Tax liability, credits and interest computations were remitted for verification and correction.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4905