Restricted silver imports may clear under a valid import authorisation without additional status or exchange-routing requirements unless expressly imp...
Head Office cost allocation requires prescribed transfer-pricing methods; treaty ceilings bar surcharge and cess, while duplicate taxation is excluded...
Cost-to-cost reimbursement of seconded employees is not service consideration; transfer-pricing markup was deleted and amalgamation amortisation allow...
Crystallisation of liability supports prior-period expense deduction, while functionally distinct divisions require separate transfer-pricing benchmar...
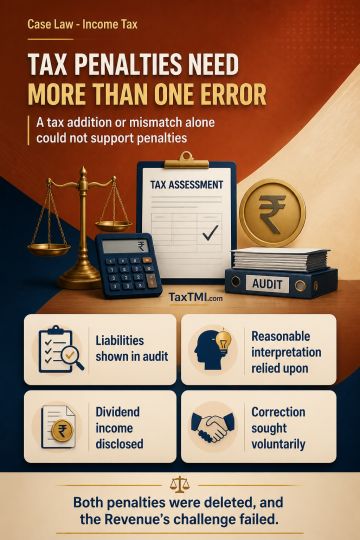
Penalty under Section 271(1)(c) does not follow merely from a Section 43B disallowance where statutory tax liabilities were not claimed as expenditure, were disclosed in the tax audit report, and rested on a plausible interpretation; a quantum addition alone does not establish inaccurate particulars. Foreign dividend income disclosed in Schedule SI and taxed at the applicable special rate is not concealed merely because it was omitted from the computation summary, where the mismatch was inadvertent and rectification was voluntarily sought before revisionary proceedings. Penalties relating to both items were deleted, and the Revenue's challenge failed.
Penalty under Section 271(1)(c) does not follow merely from a Section 43B disallowance where statutory tax liabilities were not claimed as expenditure, were disclosed in the tax audit report, and rested on a plausible interpretation; a quantum addition alone does not establish inaccurate particulars. Foreign dividend income disclosed in Schedule SI and taxed at the applicable special rate is not concealed merely because it was omitted from the computation summary, where the mismatch was inadvertent and rectification was voluntarily sought before revisionary proceedings. Penalties relating to both items were deleted, and the Revenue's challenge failed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4905