Capital Asset Conversion Requires Proven Business Stock Treatment; Paper Consideration in Spousal Flat Transfers Does Not Create Taxable Business Inco...
Human-probability test defeats political donation deduction where banking records mask accommodation-entry fund layering and evidence shows non-genuin...
Commercial property status protects capital-gains exemption when residential-house ownership limits are tested, while agricultural-land character gove...
Investigation deposits refunded after failed customs demands fall outside the statutory appellate pre-deposit interest regime and may attract compensa...
Resolution plan finality extinguishes unquantified operational-creditor claims and pending proceedings unless the approved plan expressly preserves th...
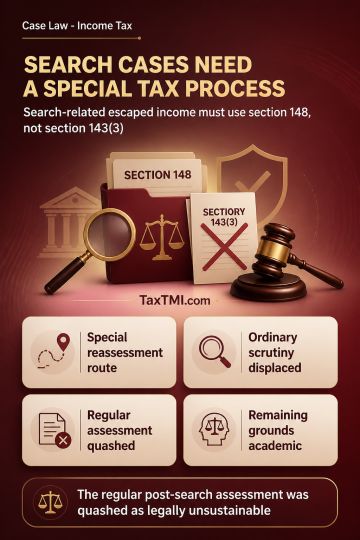
Following a search under section 132, assessment of search-related escaped income must proceed through the special reassessment mechanism under section 148 rather than the general scrutiny-assessment route under section 143(3). Consequently, a regular assessment made under section 143(3) for the relevant post-search assessment was treated as unsustainable in law and quashed, rendering the remaining grounds academic. The principle limits recourse to ordinary scrutiny assessment where the prescribed search-linked reassessment framework applies.
Following a search under section 132, assessment of search-related escaped income must proceed through the special reassessment mechanism under section 148 rather than the general scrutiny-assessment route under section 143(3). Consequently, a regular assessment made under section 143(3) for the relevant post-search assessment was treated as unsustainable in law and quashed, rendering the remaining grounds academic. The principle limits recourse to ordinary scrutiny assessment where the prescribed search-linked reassessment framework applies.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918