Blocked input tax credit for resort construction remains unavailable; interest follows actual utilisation, while delayed payment attracts statutory pe...
Duplicate PAN allocation requires record verification and deactivation reasons before assessment-related transactions can be attributed to an assessee...
Faceless assessment safeguards require requested personal hearings and adequate final show-cause response time, failing which reassessment is required...
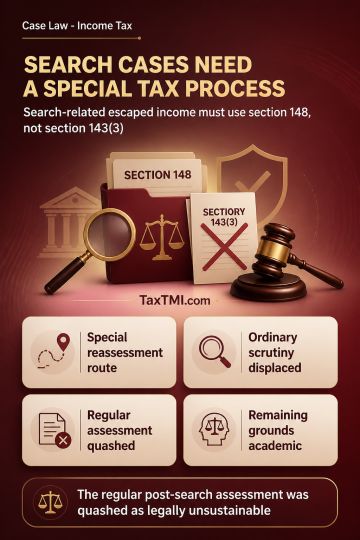
Following a search under section 132, assessment of search-related escaped income must proceed through the special reassessment mechanism under section 148 rather than the general scrutiny-assessment route under section 143(3). Consequently, a regular assessment made under section 143(3) for the relevant post-search assessment was treated as unsustainable in law and quashed, rendering the remaining grounds academic. The principle limits recourse to ordinary scrutiny assessment where the prescribed search-linked reassessment framework applies.
Following a search under section 132, assessment of search-related escaped income must proceed through the special reassessment mechanism under section 148 rather than the general scrutiny-assessment route under section 143(3). Consequently, a regular assessment made under section 143(3) for the relevant post-search assessment was treated as unsustainable in law and quashed, rendering the remaining grounds academic. The principle limits recourse to ordinary scrutiny assessment where the prescribed search-linked reassessment framework applies.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4910