Loading...

⚠ ✕
❮ Top
☎ Help
☰
×

By creating an account you can:

Logo TaxTMI
Call Us / Help / Feedback✕

Contact Us At :

✉ E-mail: [email protected]

✆ Call / WhatsApp at: +91 99117 96707

For more information, Check Contact Us

FAQs :

To know Frequently Asked Questions, Check FAQs

Most Asked Video Tutorials :

For more tutorials, Check Video Tutorials

Submit Feedback/Suggestion :

Email :
Please provide your email address so we can follow up on your feedback.
Category :
Description :
Min 15 characters 0/2000
Make Most of Text Search ✕
  1. Checkout this video tutorial: How to search effectively on TaxTMI.
  2. Put words in double quotes for exact word search, eg: "income tax"
  3. Avoid noise words such as : 'and, of, the, a'
  4. Sort by Relevance to get the most relevant document.
  5. Press Enter to add multiple terms/multiple phrases, and then click on Search to Search.
  6. Text Search
  7. The system will try to fetch results that contains ALL your words.
  8. Once you add keywords, you'll see a new 'Search In' filter that makes your results even more precise.
  9. Text Search
╳
Add to...
You have not created any category. Kindly create one to bookmark this item!
✕
Create New Category
Hide
Title :
Description :
❮❮ Hide
❮ Default View
Expand ❯❯
Close ✕
🔎 Filters / Advanced Search ❯
TEXT

Press 'Enter' to add multiple search terms. Rules for Better Search

Search In
Main Text + AI Text ❯
  • Main Text
  • Main Text + AI Text
  • AI Text
Law:
---- All Laws---- ❯
  • ---- All Laws----
  • Income Tax
  • Direct Taxes
  • Benami Property
  • Central GST Laws
  • SGST - State GST Laws
  • Customs
  • FTP - Foreign Trade Policy
  • SEZ - Special Economic Zone
  • FEMA - Foreign Exchange Management
  • Companies Law
  • SEBI - Securities & Exchange Board of India
  • IBC - Insolvency and Bankruptcy
  • Law of Competition
  • PMLA - Money-Laundering
  • Indian Laws
  • Bill / Finance Bills
  • Wealth Tax
  • Service Tax
  • Central Excise
  • VAT / Sales Tax
Month:
---- All Months ---- ❯
  • ---- All Months ----
  • January
  • February
  • March
  • April
  • May
  • June
  • July
  • August
  • September
  • October
  • November
  • December
Year:
---- All Years ---- ❯
  • ---- All Years ----
  • 2026
  • 2025
  • 2024
  • 2023
  • 2022
  • 2021
  • 2020
  • 2019
  • 2018
  • 2017
  • 2016
  • 2015
  • 2014
  • 2013
  • 2012
  • 2011
Sort By: ?
In Sort By 'Default', exact matches for text search are shown at the top, followed by the remaining results in their regular order.
Relevance Default Date
☰   Show Results ❯
    SEZ designation for Greater Noida IT site establishes approval oversight and Inland Container Depot status.
    Rules of Origin for India-New Zealand Trade Define Preferential Tariff Eligibility, Documentation, Verification, and Enforcement Requirements
    Prepared Culture Media Export Certification Enables Shipment Clearance and Health Certificates When Importing Countries Require Them
    Self-declaration-based silver bullion import authorisations enable expedited processing while retaining regulated sourcing, verification, and non-exte...
    INR non-deliverable derivatives now require hedging purpose, while Authorised Dealers must maintain foreign exchange risk reserves.
    RoDTEP scroll eligibility resumes after Annual RoDTEP Return compliance and ICES alert revocation for affected Shipping Bills.
    Subsisting judicial restraint shields employers from Section 201 default for LTC payments during the restraint period.
    Mandatory detention deadlines invalidate late GST penalty proceedings despite later confiscation action and protect hearing and appeal rights.
    Inverted-duty refunds may include higher-tax packing-material credit where qualifying inputs cause accumulation despite principal-input rate parity.
    Country-of-origin certificate verification must be consignment-specific; unrelated adverse findings cannot defeat preferential customs duty claims wit...
    GST offence classification determines whether arrest and bail restrictions apply, while continued custody requires an individualised necessity assessm...
    GST electronic authentication requires a prescribed signature; portal upload, DRC summaries, reference numbers and DIN cannot validate unsigned demand...
    Cross-assignment suspension of insolvency professionals faces proportionality and hearing limits, while creditor committees retain replacement decisio...
    October 14, 2026   Notes Money Laundering
    Equivalent-value attachment under the PMLA may reach pre-offence assets when proceeds vanish, subject to recorded reasons and demonstrable risk.
    Proper-officer jurisdiction under customs law permits assigned officers to issue recovery notices without being original assessors.
    Dependent-agent PE requires habitual authority to negotiate and conclude contracts, not customer-facing liaison or group dependence.
    GST pre-deposit shortfalls require notice and a hearing before appeal dismissal, with investigation deposits considered.
    Omission without a saving clause invalidates pending GST proceedings founded solely on an omitted rule.
    Contractual GST recovery depends on tender terms; a GST-inclusive fee does not permit separate collection or reimbursement.
    Statutory GST appellate remedy governs cross-examination disputes, leaving the necessity of examining revenue officers for appellate merits review.
❮
❯
❯❯
Maximize Maximize Maximize
0 / 200
Expand Note
Add to Folder

No Folders have been created

+

Are you sure you want to delete "My most important" ?

NOTE:

Highlights
Showing Results for :
Reset Filters
Results Found:
Show All Summaries Hide All Summaries

Highlights

Back

All Highlights

Showing Results for :
Reset Filters
No Records Found

Highlights

Back

All Highlights

Jewellery found in an assessee's locker was treated as explained...

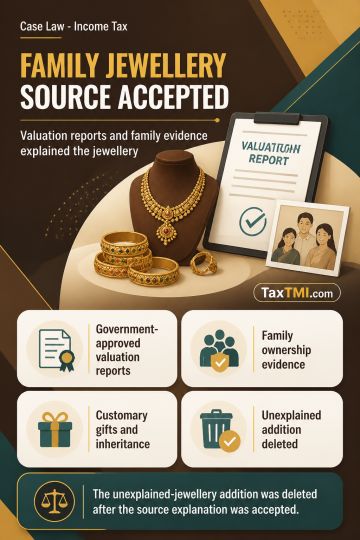
Family Jewellery Source Explanation: Valuation reports and family ownership evidence supported deletion of the unexplained-income addition.

Contents
Summary
Note

Note

-

Bookmark

Print

Print

Income Tax October 5, 2026 Case Laws AT
Jewellery found in an assessee's locker was treated as explained where government-approved valuation reports established its age and ownership by the assessee and family members. CBDT Instruction No. 1916 serves as a guiding consideration for jewellery attributable to family members, assessed with reference to family status, customary gifts and inheritance, and the surrounding circumstances. On these facts, the explanation of source was accepted and the addition for unexplained jewellery was deleted.

Topics

Acts Income Tax