Suspension of insolvency professional registration prevents continued Resolution Professional appointments and restricts interim stays that effectivel...
Original works exemption for railway contracts depends on actual integrated construction scope, while accessible tax data defeats suppression allegati...
Survey surrender characterisation determines whether mixed excess stock and business-linked cash face normal taxation or special deemed-income taxatio...
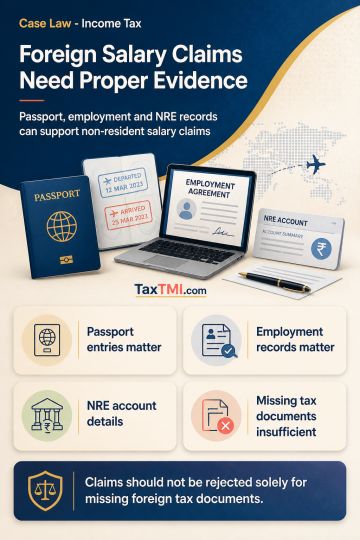
Foreign salary earned by a non-resident and received in USD in an NRE account requires assessment of evidence establishing foreign employment, non-residential status, and receipt of salary. Passport entries, employment records, and NRE account details are material evidence and should be considered. The absence of foreign tax returns, a tax residency certificate, or proof of foreign tax payment does not alone warrant rejection of the claim where available records support it. Assessment should address these documents without treating foreign tax records as a mandatory condition.
Foreign salary earned by a non-resident and received in USD in an NRE account requires assessment of evidence establishing foreign employment, non-residential status, and receipt of salary. Passport entries, employment records, and NRE account details are material evidence and should be considered. The absence of foreign tax returns, a tax residency certificate, or proof of foreign tax payment does not alone warrant rejection of the claim where available records support it. Assessment should address these documents without treating foreign tax records as a mandatory condition.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4910